
Quick Answer: What is the best investment in Pakistan for a beginner?
There is no single winner when choosing the best investment in Pakistan. If you are starting with around Rs. 5,000 and want relatively low volatility, a SECP-regulated money market mutual fund may be a practical starting point. For growth over five years or longer, compare diversified equity funds and Pakistan Stock Exchange (PSX) ETFs. For a predictable government savings arrangement, consider National Savings products suited to your eligibility and timeline. Gold can diversify savings, but its price can fall. None of these choices is universally risk-free.
Saved your first Rs. 5,000 or Rs. 50,000? One friend suggests stocks, another gold, and a bank mentions mutual funds. Where should your money go?
Investing in Pakistan can feel complicated at first, but you need only three starting questions: When do I need this money? How much loss can I tolerate? Do I want long-term growth or regular monthly income?
Here are four regulated routes in Pakistan, their real rules, tax trade-offs and how to begin—written as an educational comparison, not a personalized product recommendation.
Table of Contents
How to Choose the Best Investment in Pakistan for Your Goal
Start with your financial goal and timeline, not last year’s headline returns. A house deposit or tuition payment needed within twelve months belongs in a completely different risk category from retirement money you will not touch for ten years.
| Starting budget | Goal and time horizon | Risk tolerance | Option worth researching | Important catch |
|---|---|---|---|---|
| Rs. 5,000–10,000 | Keep short-term savings accessible | Low | Money market mutual fund | Low risk is not zero risk; check withdrawal timing and charges. |
| Rs. 5,000 each month | Long-term growth, 5+ years | Medium–high | Diversified equity/index-tracker fund or PSX ETF | Prices can drop sharply; fees and minimums differ. |
| Rs. 50,000+ | Receive monthly income | Low–medium | National Savings Regular Income Certificate | Conventional product; fixed term, taxes and early-exit charges apply. |
| Rs. 100,000+ | Build a long-term portfolio | Medium–high | Mix of diversified funds or ETFs | Diversification reduces concentration, not market-wide losses. |
| Any affordable allocation | Diversify beyond financial assets | Medium–high | Physical gold or a gold-focused fund | No reliable monthly income; storage, spreads and price risk. |
Before investing a single rupee: Keep emergency cash accessible in a liquid bank account first. Under the State Bank of Pakistan’s (SBP) Deposit Protection Corporation (DPC) rules (effective October 1, 2024 per DPC Circular Letter No. 03 of 2024), eligible deposits at member scheduled banks are protected up to Rs. 1,000,000 per depositor per bank.
Under SBP BPRD Circular Letter No. 15 of 2026 (effective August 1, 2026), the Minimum Profit Rate (MPR) floor—50 basis points below the SBP repo floor, or 10.00% p.a. as of October 2026 while the SBP policy rate stands at 11.50% per the September 14, 2026 Monetary Policy Statement—applies to individual bank savings balances up to Rs. 10 million.
Check your FBR tax status first: When evaluating the best investment in Pakistan, whether your CNIC appears on the Federal Board of Revenue (FBR) Active Taxpayers List (ATL) directly changes your net take-home return. Under the FBR Tax Year 2027 Withholding Tax Rate Card (Finance Act 2026) and the Income Tax Ordinance, 2001 (amended up to June 30, 2026), non-filers face double the withholding tax rate of ATL filers across most savings and investment channels:
| Investment / Income Type | Tax Section / Schedule | ATL Filer Rate (TY2027) | Non-Filer Rate (TY2027) | Key Statutory Note |
|---|---|---|---|---|
| National Savings profit (RIC, SSC, DSC, STSC, SA, SISA/SITA) | Section 151(1)(c) / Div. IA | 15% | 30% | Applies across profit brackets; Behbood & PBA are exempt from WHT under Second Schedule Part IV cl. 36A (taxable via return capped at 5%). |
| Bank savings & term deposit profit | Section 151(1)(a) / s. 7B | 20% | 40% | Withheld at source by banking companies and financial institutions. |
| Mutual fund dividends (debt-income portion) | Section 150 / Div. I (ba) | 25% | 50% | Applies proportionally to income derived from debt securities (money market & income funds). |
| Corporate share & equity fund dividends | Section 150 / Div. I | 15% | 30% | Applies to listed company cash dividends and the equity-income portion of mutual funds. |
| Capital Gains Tax (CGT) on listed shares & mutual fund redemptions | Section 37A / Div. VII | 15% | 30% (NCCPL table) / Slab rates (min 15%) | Applies to securities acquired on or after July 1, 2024; investor must be on ATL at both purchase and sale for the 15% filer rate. |
If you require halal investment in Pakistan, check each product’s current Shariah advisor certificate, screening criteria, and income-purification rules before committing capital.
1. Mutual Funds: A Practical Starting Point With Rs. 5,000
For many beginners researching the best investment in Pakistan with a modest budget, a regulated mutual fund is the most accessible starting point. A mutual fund pools investors’ money under a defined mandate, so you buy fund units rather than selecting every underlying instrument yourself. Asset Management Companies (AMCs) operate under the Securities and Exchange Commission of Pakistan (SECP) Mutual Fund framework, and the Mutual Funds Association of Pakistan (MUFAP) publishes daily Net Asset Values (NAVs) and category performance.
Crucially, under SECP rules, a mutual fund is established as a legal trust: all fund assets and cash are held in custody by an independent SECP-registered Trustee (such as the Central Depository Company, CDC), never in the AMC’s own corporate bank account. Even when you invest online, your payment goes to the Trustee account in the name of the fund.
Money market funds vs. equity funds
A money market fund holds short-term, high-grade liquid debt instruments (such as Treasury bills, short-term government sukuk, and bank placements), seeking capital stability and easy liquidity. An equity fund must keep at least 70% of its net assets invested in listed company shares, offering higher long-term growth potential alongside sharp short-term drawdowns.
MUFAP’s investor guidance characterizes money market funds as very low volatility and equity funds as very high volatility. In MUFAP’s 365-day performance ranking through August 31, 2026, the 26 conventional money market funds posted historical annualized returns between 9.27% and 11.05% (median 10.33%, net of fund expenses), while the 29 Shariah-compliant money market funds ranged from 9.33% to 11.03% (median 10.40%).
Over the same 365-day window, conventional equity funds ranged widely from 4.70% to 45.42%—illustrating both the upside dispersion and the market risk. Historical returns are never a guarantee of future results, and a money market fund is not a bank deposit covered by DPC insurance.
How to invest in mutual funds in Pakistan
- Choose a category first. For near-term cash reserves or emergency buffers, explore money market funds; for five-year-plus wealth building, research diversified equity or index-tracker funds (which must keep at least 85% of net assets in index constituents).
- Verify the AMC license. Check official SECP NBFC licensing records and open accounts only through the AMC’s verified website or mobile portal—never through a WhatsApp or Telegram tip group.
- Read the Fund Manager Report (FMR) and Offering Document. Under SECP’s Expense Regime amendments effective July 1, 2025, management fees are capped at up to 1.5% p.a. for money market and income schemes and up to 3.0% p.a. for equity schemes. Also check the Total Expense Ratio (TER) and sales load: SECP caps front-end sales loads at 3% of NAV, and mandates a 0% sales load when you approach the AMC directly or invest online through its website.
- Open an online investment account. Most licensed AMCs offer digital onboarding using your CNIC, mobile number, IBAN, and KYC verification, with redemptions legally required to be paid within a maximum of six working days (and often faster for money market funds).
- Make a small first contribution. As one verified example, Meezan Cash Fund lists Rs. 5,000 initially and Rs. 1,000 for subsequent investments. Other funds can set different minimums. Source: Al Meezan fund facts.
What about Shariah-compliant mutual funds?
Pakistan offers Shariah-compliant money market, income, equity, and commodity funds. Review the permissible holdings, Annual Shariah Advisor’s Report, and charity/purification policies in the latest Fund Manager Report. Islamic money market and income funds invest in GoP Ijarah Sukuk, corporate sukuk, and Islamic bank placements, whereas Islamic equity funds screen companies for core business permissibility and financial ratios. Al Meezan identifies Meezan Cash Fund as Shariah-compliant; not every mutual fund is. Remember that halal status governs how the fund invests, not whether its unit price can fluctuate.
2. Pakistan Stock Exchange: Shares, ETFs and the Sahulat Account
The Pakistan Stock Exchange (PSX) trades listed company shares, exchange-traded funds (ETFs), and government debt securities. Buying an individual share gives you fractional ownership in a single business; buying an ETF gives you a basket of listed securities in one trade, often tracking a benchmark index. ETFs still rise and fall with the stock market, but they reduce single-company concentration risk.
Avoid buying an individual stock merely because social media promotes it. Since April 22, 2024 (PSX Notice 228948-1), PSX allows investors to buy as little as 1 share of any listed company in the Ready Market, while PSX-listed ETFs trade in 500-unit board lots in the regular market (or 1 unit in the odd-lot market). Compare ETF benchmarks, management fees, and market-maker liquidity in the official PSX ETF guide.
How to invest in Pakistan Stock Exchange online
- Choose a licensed TREC-holder broker. Verify that the brokerage is recognized by PSX and licensed by SECP. Under PSX Notice PSX/N-1258, standard Ready Market brokerage commission starts at a regulatory minimum of the higher of 3 paisa (Rs. 0.03) per share or 0.15% of transaction value (capped at 2.5%). Compare broker apps, tariff schedules, and account safety using PSX’s investor guidance.
- Ask about a Sahulat Account. Designed for beginners, the Sahulat Account offers simplified digital onboarding for eligible resident Pakistani individuals using only your CNIC and personal bank account IBAN, without requiring complex income-proof paperwork upfront.
- Complete identity, biometric and bank checks. Provide your CNIC, mobile number registered in your own name, IBAN, and any biometric or KYC verification the broker legitimately requests through the centralized NCCPL/CDC onboarding system.
- Confirm CDC custody and NCCPL registration. Your shares are held electronically in a Central Depository Company (CDC) Sub-Account (which carries a standard annual maintenance fee of Rs. 400 per CDC’s August 2026 fee schedule) or a direct CDC Investor Account, and your trades settle on a T+1 (one business day) cycle linked to your Unique Identification Number (UIN) at the National Clearing Company of Pakistan (NCCPL).
- Transfer funds only through approved banking channels. Never hand cash to an agent; pay only from your own bank account to the broker’s designated client-segregated bank account, and keep all trade confirmations and CDC statements.
Following PSX and SECP reforms in March and April 2026 (PSX Notice PSX/N-374, verified October 2026), the Sahulat Account position limit is Rs. 3 million per brokerage account. It restricts trading to the Ready Delivery Contract Market (blocking leveraged futures and margin financing so beginners cannot face forced margin-call liquidations) and permits one Sahulat Account per investor with each broker across multiple brokers. Check the current PSX Sahulat page before applying, as account rules can change.
3. National Savings: Lower-Risk Government Savings Options
Operated by the Central Directorate of National Savings (CDNS), an attached department of Pakistan’s Ministry of Finance, National Savings schemes are popular among conservative savers and retirees. Before choosing any certificate, ask three questions: Who is eligible, when is profit paid, and what deduction applies if I encash early?
| CDNS Scheme | Minimum Investment | Maturity & Payout Frequency | Early Encashment Rule | Withholding Tax & Zakat |
|---|---|---|---|---|
| Defence Savings Certificates (DSC) | Rs. 500 (no max) | 10-year term; cumulative profit paid at encashment/maturity | Encashable anytime at par, but zero profit is paid if encashed before 1 complete year. | 15% ATL filer / 30% non-filer WHT; Zakat deducted at source per rules. |
| Behbood Savings Certificates (BSC) | Rs. 5,000 (max Rs. 7.5M single) | 10-year term; monthly profit | Service charge of 1%, 0.75%, 0.50%, and 0.25% of face value if encashed before years 1, 2, 3, or 4. | Senior citizens (60+), widows & qualifying disabled persons only; no WHT deducted at source; Zakat exempt. |
| Regular Income Certificates (RIC) | Rs. 50,000 (no max) | 5-year term; monthly profit | Service charge of 2%, 1.50%, 1%, and 0.50% of face value if encashed before years 1, 2, 3, or 4. | 15% ATL filer / 30% non-filer WHT; exempt from Zakat collection at source. |
| Short-Term Savings Certificates (STSC) | Rs. 10,000 (no max) | 3, 6, or 12 months; paid at maturity | Can be encashed after 1 month, but profit is payable only upon completing full maturity. | 15% ATL filer / 30% non-filer WHT; exempt from Zakat collection at source. |
| Sarwa Islamic Savings / Term Account (SISA / SITA) | Per Rafa National Savings rules | SISA: monthly expected; SITA: 1, 3, or 5-year terms | Governed by Rafa National Savings Shariah window rules. | 15% ATL filer / 30% non-filer WHT; 2.5% Zakat & service charges per rules. |
Defence Savings Certificates (DSC) are built for multi-year compounding with a 10-year maturity, starting from Rs. 500. They are not a substitute for a monthly income check because profit accumulates on a stepped annual schedule and no profit is paid if you withdraw before completing one full year. See official Defence Savings Certificate terms.
Behbood Savings Certificates (BSC) pay profit monthly and are exempt from withholding tax deduction at source and Zakat, but they are strictly restricted to eligible Pakistani senior citizens aged 60 or above, widows (who remain unmarried), and qualifying persons with disabilities. The minimum investment is Rs. 5,000 up to Rs. 7.5 million for a single investor, with early-encashment service charges during the first four years. See official Behbood Savings Certificate terms.
Regular Income Certificates (RIC) are open to the general adult public, start at Rs. 50,000 with no maximum limit, and distribute profit monthly over a five-year term. However, redeeming before four years triggers a principal service charge between 0.50% and 2.00% of face value, and monthly payouts face 15% withholding tax for ATL filers (or 30% for non-filers). See official Regular Income Certificate terms.
Even government-administered savings products carry inflation, tax, and liquidity trade-offs. Always verify the current National Savings profit rate schedule before investing: CDNS revised its official profit rates effective October 21, 2026 (for example, adjusting Regular Income Certificates to 12.12% p.a. gross, Behbood to 12.96% p.a., Defence Savings to 11.94% compound p.a. to maturity, and Sarwa Islamic SISA to 11.84% expected p.a. for new deposits from that date). Because CDNS revises rates periodically, always check the live schedule on the day you invest.
Need an Islamic alternative at National Savings? Conventional CDNS certificates are fixed-return debt instruments and should not be treated as Shariah-compliant. National Savings separately operates Rafa National Savings, an independent Islamic window offering the Sarwa Islamic Savings Account (SISA) and Sarwa Islamic Term Account (SITA) in 1-year, 3-year, and 5-year tenors with anticipated (non-fixed) profit rates under Shariah board oversight. Review the structure and documentation on the official National Savings Islamic-products page.
4. How to Invest in Gold in Pakistan: Physical Gold vs. a Fund
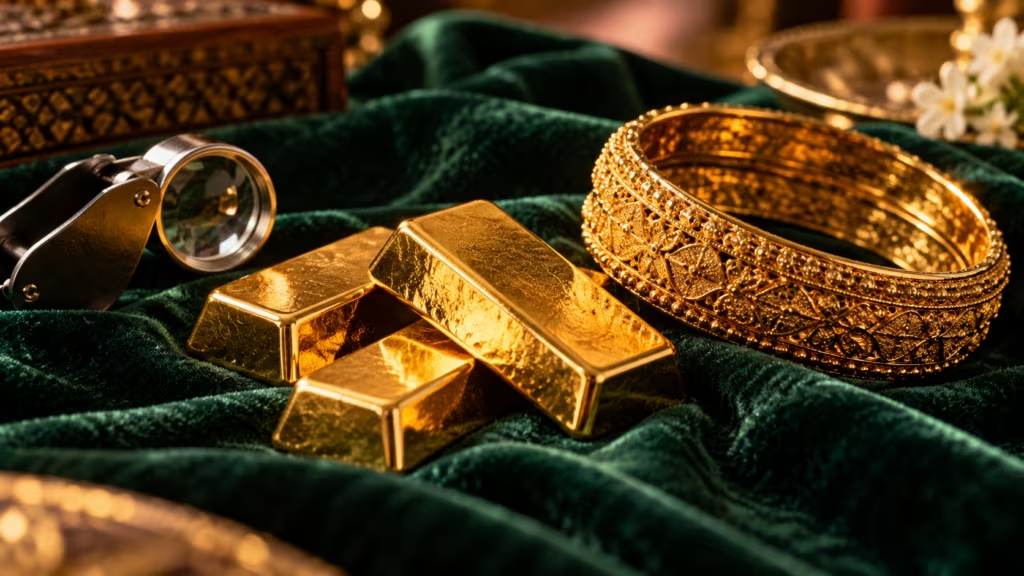
Gold has a long cultural history in Pakistani households as a hedge against currency depreciation, and many savers consider it when debating the best investment in Pakistan. However, gold produces zero monthly cash flow, and its rupee price can drop when global bullion prices fall or the Pakistani rupee strengthens.
Physical gold (bars, coins, or jewelry): Always compare the buy-back spread of reputable bullion dealers, insist on a written invoice and karat/purity assay certificate (24-karat bars or coins vs. 21k/22k jewelry), and factor in safe-deposit locker fees, home security risk, and resale deductions. Gold jewelry carries heavy making charges (mazdoori) and stone-weight deductions that are lost immediately upon resale, making certified 24-karat bars or coins more cost-efficient than jewelry for pure investment purposes.
Regulated gold mutual fund: For investors who prefer digital custody without home storage risk, Meezan Gold Fund offers Shariah-compliant gold-price exposure through an SECP-regulated open-end commodity mutual fund. Under SECP categorization rules, a commodity fund must keep at least 70% of its net assets in commodity contracts; Meezan Gold Fund invests substantially in deliverable gold-based contracts on the Pakistan Mercantile Exchange (PMEX).
It is a mutual fund rather than a PSX-traded ETF, and the provider classifies its risk profile as high. Its stated initial investment is Rs. 5,000 (with Rs. 1,000 for subsequent contributions); review the management fee, price-benchmark tracking, and redemption rules in the latest offering document. Source: Al Meezan Meezan Gold Fund.
If your goal is to pay rent or university fees next month, neither physical gold nor a gold fund is a safe substitute for liquid cash. And if halal compliance matters to you, verify both the gold product’s Shariah advisor certification and spot-settlement structure rather than relying on the word “gold” alone.
What Is the Best Investment Plan for Monthly Income in Pakistan?
If you are looking for the best investment in Pakistan for monthly income, separate regular cash payouts from long-term capital appreciation. An equity fund or gold bar may rise in value over five years without paying you a single rupee of monthly cash, and selling units during a market downturn to pay bills can permanently erode your principal.
For an adult resident seeking a conventional monthly payout from Rs. 50,000 or more, National Savings Regular Income Certificates (RIC) pay profit monthly (subject to 15% filer / 30% non-filer withholding tax and early-withdrawal charges if redeemed within four years). Behbood Savings Certificates pay monthly profit without withholding tax deduction at source, but only if you meet the strict senior-citizen, widow, or disability eligibility criteria.
For a Shariah-compliant monthly income plan, compare the monthly distribution options of SECP-regulated Islamic money market or income mutual funds and the Sarwa Islamic Savings Account (SISA) / 5-year Sarwa Islamic Term Account (SITA). Never assume that a past annualized yield guarantees an identical future monthly rupee payout.
A Simple First-30-Days Investment Plan
You do not need to rush your life savings into the market on day one. Follow this four-week checklist to move from saver to informed investor safely:
- Week 1 — Audit your cash buffer and tax status: Write down your goal, when you will need the money, your emergency cash reserve (at least three to six months of essential expenses in a DPC-protected bank account), and any high-cost debt. Confirm whether your CNIC is active on FBR’s Active Taxpayers List (ATL) so you do not lose double the return to non-filer withholding tax.
- Week 2 — Shortlist two regulated options in the right risk bucket: Match your time horizon to the table above—such as two SECP-licensed money market funds for short-term cash or two diversified index/equity options for a five-year-plus horizon. Download the latest Fund Manager Reports or official CDNS/PSX product terms.
- Week 3 — Verify licenses, Shariah reports and total costs: Confirm the institution on the official SECP, PSX, MUFAP, or National Savings website. Check the management fee, Total Expense Ratio (TER), online 0% sales-load eligibility, early-encashment rules, Zakat (or CZ-50 declaration deadline), and FBR tax rate.
- Week 4 — Start with a small test transfer from your own bank account: Open the account directly through the official portal, transfer an affordable starter amount (such as Rs. 5,000), verify your electronic statement or CDC confirmation, and review your progress quarterly rather than checking prices every hour.
The core wealth-building habit—spend less than you earn, start modestly, diversify across regulated assets, and let compounding work over years—applies everywhere. The account structures and tax laws do not. For a Pakistan-specific fund walkthrough, see our Mutual Funds in Pakistan guide.
Frequently Asked Questions
Which investment gives the highest return in Pakistan?
There is no investment that reliably delivers the highest return. Individual stocks, equity funds and gold can post strong gains in some periods and substantial losses in others. National Savings publishes product-specific profit schedules, but compare the scheme’s terms, taxes and eligibility rather than ranking everything by one headline percentage. The best choice depends on risk and when you need your money.
What if I invest Rs. 5,000 per month?
You would contribute Rs. 60,000 in one year and Rs. 300,000 over five years, before any profit, loss, fees or taxes. A consistent monthly contribution can help you build a habit. Choose an investment with minimums and volatility you can actually sustain; an equity fund is not suitable for money you must withdraw next month.
Is investing in the PSX halal?
Some PSX investments can be Shariah-compliant, but not every stock or trading method is halal. PSX publishes Shariah-focused indices such as KMI-30 and lists Shariah-compliant products, including the Meezan Pakistan ETF. Review a security’s current screening status and the relevant Shariah guidance, and avoid assuming that leveraged or interest-based arrangements qualify. See the PSX Shariah investing overview.
How does FBR Filer vs. Non-Filer status affect investment returns in Pakistan?
Being on the Federal Board of Revenue (FBR) Active Taxpayers List (ATL) significantly reduces withholding tax on investment returns. Under the FBR Tax Year 2027 Withholding Tax Rate Card (Finance Act 2026), ATL filers face 15% withholding tax on most National Savings profits versus 30% for non-filers, 20% versus 40% on bank profit, and 15% (equity) or 25% (debt) on mutual fund dividends versus 30% or 50% for non-filers.
Are mutual funds or National Savings covered by SBP bank deposit protection?
No. The State Bank of Pakistan’s Deposit Protection Corporation (DPC) protects eligible bank deposits at member scheduled banks up to Rs. 1,000,000 per depositor per bank. Mutual fund units are subject to market risk and are excluded from DPC coverage, while National Savings (CDNS) operates separately as an attached department of the Ministry of Finance rather than a DPC member bank.
The Bottom Line
Ultimately, the best investment in Pakistan is not the one with the loudest social-media promise or the highest single-year chart. It is the regulated option that fits your timeline, your capacity to absorb market fluctuations, your FBR tax position, and your requirements for Shariah compliance. For many beginners, that journey starts with Rs. 5,000 in a transparent, low-volatility mutual fund or a PSX Sahulat Account after building an emergency buffer. Take the time to read two official offering documents today—your future self will thank you for checking the rules before sending the money.
Official Sources and Regulatory References
- Securities and Exchange Commission of Pakistan (SECP) — Mutual Fund Investor Guide & NBFC Licensing
- SECP — Notification on Mutual Fund Expense Regime & Shariah Compliance Amendments (Effective July 1, 2025)
- Mutual Funds Association of Pakistan (MUFAP) — 365-Day Ranking of Collective Investment Schemes (August 2026)
- Pakistan Stock Exchange (PSX) — Sahulat Account Rules & Notice PSX/N-374 (Rs. 3 Million Limit, April 2026)
- Pakistan Stock Exchange (PSX) — Exchange Traded Funds (ETFs) & Shariah Investing Overview
- Central Depository Company of Pakistan (CDC) — Sub-Account & Custody Fee Schedule (Updated August 2026)
- National Clearing Company of Pakistan Limited (NCCPL) — Capital Gains Tax (CGT) Tariff & Settlement Rules
- Central Directorate of National Savings (CDNS) — Official Profit Rates Schedule (Effective October 21, 2026) & Scheme Rules
- Federal Board of Revenue (FBR) — Withholding Income Tax Rate Card for Tax Year 2027 (Finance Act 2026)
- State Bank of Pakistan (SBP) — Monetary Policy Statement (September 14, 2026) & BPRD Circular Letter No. 15 of 2026
- Deposit Protection Corporation (DPC, Subsidiary of SBP) — Rs. 1,000,000 Depositor Protection Rules
Financial disclaimer: MoneyPulsar provides independent educational information, not personalized investment, tax, legal or Shariah advice. It is not an SECP-licensed investment adviser or broker. Mutual funds, shares, ETFs and gold may lose value, including principal; lower-risk funds are not guaranteed deposits. Government savings products have eligibility, maturity, early-redemption and other terms, and published rates or tax treatments may change. Past performance is not a promise of future results. Verify current details with SECP, PSX, MUFAP, National Savings and the product provider, and consult a qualified Pakistan-based financial, tax or Shariah professional where appropriate. Read MoneyPulsar’s full disclaimer and editorial policy.
Syed Hamza Hasnain · Founder & Editor
Syed Hamza Hasnain is the Founder and Editor of MoneyPulsar. He researches and edits practical guides on budgeting, debt payoff, index investing, and retirement planning across our US and Pakistan tracks using primary regulatory sources. Learn more about our editorial process →