
Retirement Savings Calculator
Hypothetical illustration only. Investment returns are uncertain and not guaranteed; real returns vary year to year and can be negative. Fees, taxes, contribution limits and changes to your plans are not included.
This calculator is for education and is not financial, investment or tax advice. Consider speaking with a qualified, licensed professional about your situation. Your inputs stay in your browser and are not stored.
How this calculator works (method)
1. Monthly rate from the effective annual return: r_m = (1 + r_a)^(1/12) − 1. So 7% a year becomes about 0.5654% a month (not 7% ÷ 12).
2. Number of months: n = 12 × (retirement age − current age).
3. Monthly deposit C = your contribution + employer contribution, added at the end of each month.
4. Future value: FV = B × (1 + r_m)^n + C × ((1 + r_m)^n − 1) ÷ r_m, where B is your current balance. If the return is 0%, FV = B + C × n.
5. Today's dollars: Real FV = FV ÷ (1 + inflation)^years.
6. Scenarios: low = your return − 2 percentage points (not below 0%), middle = your return, high = your return + 2 points.
Retirement Calculator: Quick Answer
This free retirement calculator estimates what your savings could grow to by the age you plan to retire. Enter your age, current balance, monthly contribution, an assumed annual return and inflation. You get a projected balance, the same amount in today’s dollars, and low, middle and high scenarios. Results are hypothetical, not guaranteed.
How to Use the Retirement Calculator
- Enter your current age and the retirement age you are planning for.
- Add your current retirement balance across your 401(k), IRA and other retirement accounts.
- Enter what you put in each month. If you use it as a 401k calculator, this is your payroll deferral.
- Optionally add an employer contribution, either as a percentage of what you put in or a flat dollar amount per month.
- Set an assumed annual return and an inflation rate, then press Calculate. To try different numbers, change any field and press Calculate again.
How the Retirement Calculator Does the Math
This retirement calculator uses a standard future-value formula with monthly compounding. Every step is shown in the “How this calculator works” panel above, so you can check it by hand.
- Monthly rate: your annual return is treated as an effective annual rate, so the monthly rate is
(1 + r)^(1/12) − 1. At 7% that is about 0.5654% a month, not 7% ÷ 12 (0.5833%). Twelve months at the monthly rate compound back to exactly 7%. - Timing: each monthly deposit is added at the end of the month, so a new deposit starts earning the following month.
- Future value: your starting balance grows for every month, and each deposit grows for the months left after it is made. At a 0% return the result is simply your balance plus all deposits.
- Inflation adjustment: the projected balance is divided by
(1 + inflation)^yearsto show roughly what it would buy in today’s dollars.
Low, Middle and High Scenarios
No one knows future returns, so the retirement calculator shows a range. The middle scenario uses the return you entered. The low scenario uses 2 percentage points less (never below 0%), and the high scenario uses 2 points more. The gap between low and high is a reminder of how much the outcome depends on an assumption you cannot control.
Worked Example: Age 30 to 65
Say you are 30, plan to retire at 65, have $10,000 saved and add $500 a month, with a 7% return and 3% inflation. That is 420 monthly deposits, so you put in $220,000 in total, including the starting balance. The retirement calculator projects:
| Scenario (annual return) | Projected balance at 65 | In today’s dollars |
|---|---|---|
| Low (5%) | $609,392 | $216,568 |
| Middle (7%) | $962,473 | $342,047 |
| High (9%) | $1,550,962 | $551,186 |
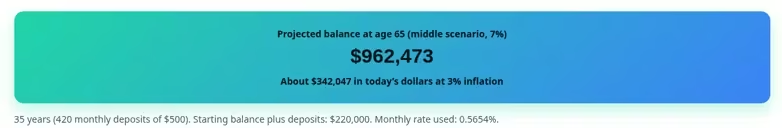
In the middle case, about $742,000 of the $962,473 comes from growth rather than deposits. Inflation matters just as much: at 3% a year for 35 years, prices roughly 2.8×, which is why the today’s-dollars figure is closer to $342,000.
What This Retirement Savings Calculator Leaves Out
A simple retirement savings calculator is useful for seeing the effect of time, contributions and returns. It is not a full plan. This retirement calculator does not include:
- Fees: fund expense ratios and advisory fees reduce real-world growth.
- Taxes: results are pre-tax. Traditional 401(k) and IRA withdrawals are generally taxed; Roth rules differ.
- Employer match rules: the employer field is a simple add-on with no cap, vesting schedule or salary-based limit, which most real match formulas have.
- IRS contribution limits: the tool will not stop you entering more than you are allowed. For 2026 the IRS set the 401(k) employee limit at $24,500, the catch-up for ages 50 and over at $8,000, and the IRA limit at $7,500 (IRS announcement).
- Sequence risk and volatility: it uses one steady return every year. Real returns vary and can be negative, and a downturn just before or during retirement can matter more than the average.
- Withdrawals: it stops at retirement age and does not model spending in retirement.
To try other compounding assumptions, the SEC’s Investor.gov offers a free compound interest calculator.
Next Steps
- Just starting out? Read saving for retirement in your 20s for practical first steps.
- New to investing? Our beginner’s guide to investing covers accounts and low-cost index funds.
- Need room in your budget for a bigger monthly contribution? Try these 15 budgeting tips.
- Paying off high-interest cards first? Map your debt-free date with our debt payoff calculator.
Disclaimer: This retirement calculator and article are for educational purposes only and are not financial, investment or tax advice. Projections are hypothetical and returns are not guaranteed. Read our full Financial Disclaimer.
Is this retirement calculator free?
Yes. It is free to use with no sign-up. Your inputs stay in your browser and are not stored or sent anywhere.
Why does the retirement calculator use (1 + r)^(1/12) − 1 instead of dividing by 12?
It treats your return as an effective annual rate. Taking the 12th root gives a monthly rate that compounds back to exactly that annual rate. Dividing by 12 would slightly overstate growth, because 7% ÷ 12 compounded monthly works out to about 7.23% a year.
What does “today’s dollars” mean?
It is the projected balance divided by (1 + inflation) for each year until retirement. It shows roughly what that future amount would buy at today’s prices, which is usually a more useful number for planning than the nominal total.
Can I use it as a 401k calculator?
Yes, as a rough estimate. Enter your monthly payroll deferral as your contribution and your employer’s match in the optional field. It does not apply IRS limits, which for 2026 are $24,500 for employee 401(k) deferrals plus an $8,000 catch-up from age 50, or plan rules such as match caps and vesting.
What annual return should I enter?
There is no right number, and no return is guaranteed. Enter an assumption you consider realistic for your mix of investments after fees, then look at the low and high scenarios to see how much the result changes if returns come in 2 points lower or higher.