
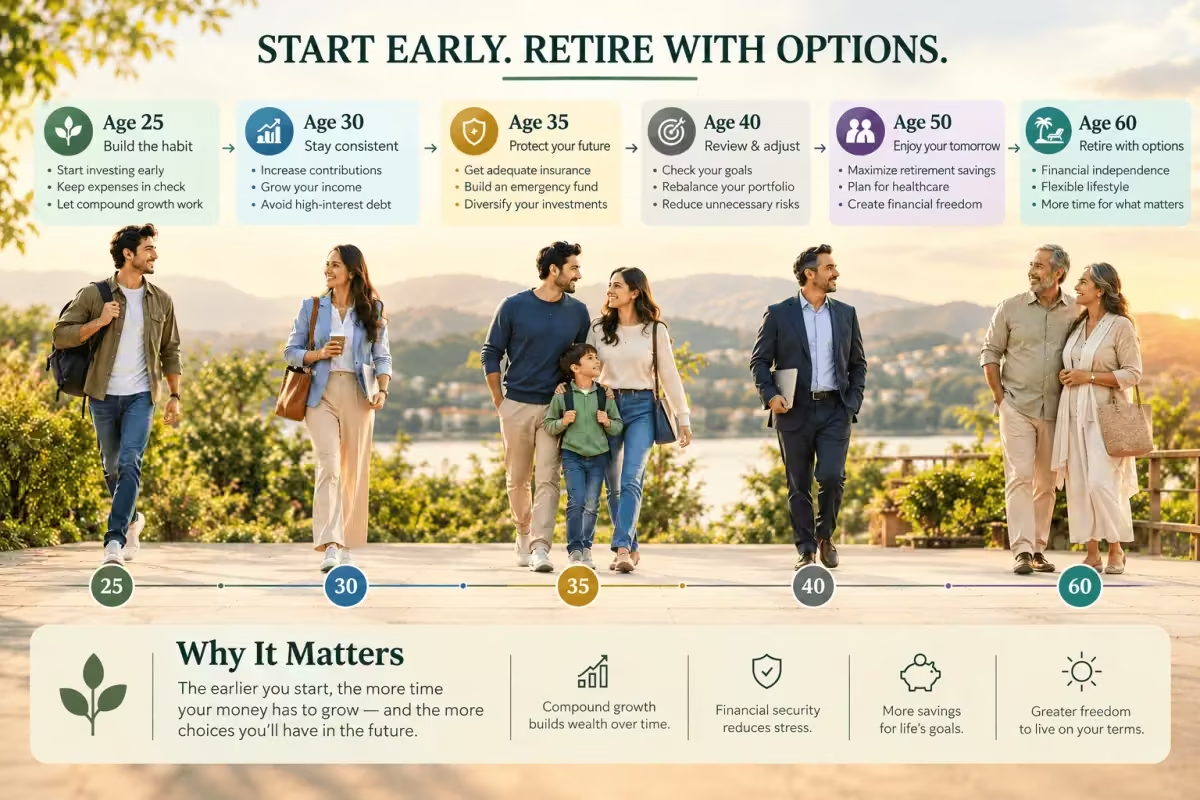
Saving for retirement in your 20s starts with a manageable monthly contribution, capturing any available 401(k) employer match, and choosing an account that fits your tax situation. Build emergency savings, address high-interest debt, automate contributions, and increase your savings rate as your income grows.
Key Takeaways:
- Starting at age 25 with $100/month builds roughly $247,154 at a 7% annual return (or ~$555,035 at 10%) by age 65 in our illustration — and participants aged 25–34 in Vanguard-administered plans had a median account balance of $18,732 in 2025, according to Vanguard’s How America Saves data
- In Vanguard’s How America Saves 2026, workplace plans with automatic enrollment had a 94% participation rate in 2025, versus 64% in plans where employees had to opt in
The 7 Steps at a Glance
- Build a starter emergency fund ($1,000 as a first milestone) in a separate high-yield savings account.
- Get the full employer 401(k) match if your plan offers one (formulas and vesting vary).
- Pay down high-interest debt, such as credit cards charging 20% APR or more (an example, not a fixed cutoff).
- Open a Roth IRA if you qualify (up to $7,500 in 2026).
- Automate your contributions so saving happens on payday.
- Choose a low-cost target-date or index fund that fits your timeline and risk tolerance.
- Raise your rate toward 15% of income, including any employer match (Fidelity guideline), adding 1% to 2% with each raise.
Why Saving for Retirement in Your 20s Matters Most
Compound Growth Chart: Starting at 22, 25, 30 or 35
Assumptions: $5,000 invested at the end of each year from the starting age until age 65, a constant 7% annual return, and no fees, taxes or withdrawals. Formula: FV = P × ((1 + r)n − 1) / r, with P = $5,000, r = 0.07 and n = 65 − starting age. At 25, that is $5,000 × ((1.07)40 − 1) / 0.07 ≈ $998,176.
| Starting Age | Years of Saving (n) | Total Contributed | Value at 65 (7%) | Growth From Returns |
|---|---|---|---|---|
| Age 22 | 43 | $215,000 | $1,238,882 | $1,023,882 |
| Age 25 | 40 | $200,000 | $998,176 | $798,176 |
| Age 30 | 35 | $175,000 | $691,184 | $516,184 |
| Age 35 | 30 | $150,000 | $472,304 | $322,304 |
How we calculated this: every projection in this guide treats 7% and 10% as effective annual returns. Yearly examples use FV = P × ((1 + r)n − 1) / r. Monthly examples convert the annual rate to an equivalent monthly rate, rm = (1 + r)1/12 − 1 (about 0.565% a month for 7% and 0.797% for 10%), with deposits at the end of each period. Values are computed in Python and rounded. If you read 7% as an inflation-adjusted (real) return, results are roughly in today’s dollars; 10% is a nominal figure and is not inflation-adjusted. Fees, taxes, employer matches and withdrawals are excluded. Limits and tax figures are checked against 2026 IRS guidance. Projections are hypothetical, not guaranteed; actual results vary with returns, inflation, fees, taxes and timing.
Why Almost Nobody Actually Does It
Retirement planning in your 20s doesn’t fail because people don’t care. Competing costs get in the way. In Transamerica’s 2025 retirement survey, more Gen Z workers named paying off debt (55%) as a current financial priority than saving for retirement (32%), and 41% said just getting by to cover basic living expenses was a priority.
Planning for Retirement in Your 20s: What You Actually Need
You’ve probably seen the Fidelity retirement guideline: have 1x your salary saved by age 30 (which assumes saving 15% of your income a year from age 25, including any employer match, investing more than 50% in stocks on average and retiring at 67). For someone earning $40,000 a year, that’s $40,000 by 30. Which, on a $40,000 salary in an expensive city, feels impossible.
To translate the Fidelity age-30 savings guideline (1x salary by 30, then 3x by 40) into realistic milestones for your 20s and early 30s, use the benchmark table below alongside the official IRS retirement contribution limits (IRS Notice 2025-67):
How to read this table: Fidelity’s guideline is a multiple of salary (1x by 30, 3x by 40) under Fidelity’s assumptions (15% saved a year from 25 including any match, more than 50% in stocks, retiring at 67). Only the age 30 row is Fidelity’s; the other rows are MoneyPulsar’s illustrative steps toward it, not Fidelity, IRS or industry benchmarks.
| Age Milestone | Savings as a Multiple of Salary | Example Target on a $50,000 Salary | Key Priority Move for 2026 (Fidelity & IRS Rules) |
|---|---|---|---|
| Age 22 (MoneyPulsar illustration) | Starter Buffer + Match (0.05x–0.1x) | $1,000 cash buffer + $2,500–$5,000 | Build a $1,000 high-yield savings emergency buffer first, then contribute enough to capture 100% of your employer’s 401(k) match. |
| Age 25 (MoneyPulsar illustration) | 0.25x–0.5x Annual Salary | $12,500 – $25,000 | Pay down high-interest credit card debt (for example, 20%+ APR) and automate monthly Roth IRA transfers (up to the $7,500 2026 IRA limit). |
| Age 28 (MoneyPulsar illustration) | 0.5x–0.75x Annual Salary | $25,000 – $37,500 | Raise your total retirement savings rate by 1%–2% after each raise toward 10%–12% of gross pay across your 401(k) and Roth IRA. |
| Age 30 (Fidelity Benchmark) | 1x Annual Salary | $50,000 | Target a 15% total annual savings rate (including employer match) and choose a diversified, low-cost allocation that matches your risk tolerance and timeline (many long-horizon investors hold mostly stock index funds). |
| Age 35 (MoneyPulsar illustration) | About 2x Annual Salary (MoneyPulsar estimate between Fidelity’s 1x at 30 and 3x at 40) | $100,000 | Scale workplace 401(k) contributions toward the IRS employee deferral ceiling ($24,500 2026 limit under age 50) while maxing out your Roth IRA. |
Pay Off Debt or Save First?
Build an emergency fund before investing: keep a $1,000 starter buffer in a high-yield savings account, separate from retirement money. It is a first milestone, not a full emergency reserve; many households will need more over time (our 15 Budgeting Tips That Actually Work in 2026 guide puts it second on the list).
Then get any employer 401(k) match, since it is part of your pay. After that, compare your debt rates with what investing might earn. Credit cards often sit far above typical return assumptions: the average APR on accounts assessed interest was 22.36% in August 2026 (Federal Reserve G.19). See your payoff timeline in our debt payoff calculator or compare methods in How to Pay Off Debt in 2026.
Student Loans vs. Investing: A Decision Framework
There is no universal answer, but these questions, in order, help frame the choice:
- Are all minimum payments covered? Staying current on every loan comes before investing beyond any match.
- Is there an employer match? Contributing enough to receive it is often prioritized because the match adds money you would otherwise not receive (subject to vesting).
- What is the loan’s interest rate? Fidelity suggests considering prioritizing debt at 6% or more once you get the full match; lower-rate loans are often paid on schedule while you keep investing.
- Federal or private? Federal loans offer repayment options, including income-driven plans where payments are based on income. Federal Student Aid’s Repayment Calculator compares the plans you are eligible for; private loans usually don’t offer federal programs such as income-driven repayment or Public Service Loan Forgiveness, so check your lender’s terms.
How to Save for Retirement in Your 20s: The 3-Step Account Order
When deciding how to save for retirement in your 20s, fund accounts in this order: first contribute enough to your workplace 401(k) to get the full employer match, second contribute to a Roth IRA (up to $7,500 in 2026), and third increase your 401(k) contribution.
Step 1: Get the Employer Match
If your job offers a 401(k) match, consider contributing at least enough to get the full match. An employer match can substantially increase your retirement contributions. For example, if your employer contributes $0.50 for every $1 you contribute, up to a specified limit, you receive an additional $0.50 in employer contributions for each eligible dollar you save (U.S. Department of Labor). Check your plan’s matching formula and vesting schedule before making assumptions about when those contributions become yours: your own contributions are always 100% vested, but employer contributions can vest over time, for example 100% after 3 years of service under a cliff schedule (IRS).
Step 2: Open a Roth IRA
A Roth IRA is often a good fit in your 20s, when your tax rate may be lower than it will be later. You pay tax on the money now, and qualified withdrawals in retirement are tax-free. Under IRS Notice 2025-67 (2026 contribution limits), you can contribute up to $7,500 in 2026 across all your traditional and Roth IRAs combined ($8,600 if 50 or older), and eligibility is based on modified adjusted gross income (MAGI), filing status and other IRS rules, phasing out at $153,000–$168,000 for single filers and $242,000–$252,000 for married couples filing jointly. The 2026 employee 401(k) deferral limit is $24,500.
Step 3: Back to the 401(k)
Once the Roth IRA is funded, raise your 401(k) contribution as your income grows. You don’t need to hit the max in your 20s.
Best Retirement Accounts for Young Adults (2026 IRS Limits)
| Account | 2026 Limit | Catch-Up | Tax Treatment | Often Suits |
|---|---|---|---|---|
| 401(k) | $24,500 employee deferral | +$8,000 at 50+; $11,250 at ages 60–63 | Traditional: pre-tax, taxed on withdrawal; Roth 401(k) (if offered): after-tax | Workers whose employer offers a match |
| Roth IRA | $7,500 (shared IRA limit); phase-out $153,000–$168,000 single | +$1,100 at 50+ | After-tax in; qualified withdrawals tax-free | Earners in a lower bracket now |
| Traditional IRA | $7,500 (shared IRA limit) | +$1,100 at 50+ | May be deductible (phase-out $81,000–$91,000 single if covered at work); withdrawals taxed | People with no workplace plan, or who want a deduction now |
| HSA | $4,400 self-only / $8,750 family (HSA-eligible plan with a $1,700 / $3,400 minimum deductible) | +$1,000 at 55+ (see IRS Pub. 969) | Deductible contributions; tax-free for qualified medical costs; no additional tax on non-medical withdrawals after 65 (income tax applies) | People enrolled in an HSA-eligible high-deductible plan |
Traditional 401(k) vs. Roth 401(k) vs. Roth IRA
The account type (401(k) or IRA) decides who offers it and the limit; the tax treatment (traditional or Roth) decides when you pay tax. Per the IRS Roth comparison chart:
- Traditional (pre-tax) 401(k): contributions are made with before-tax dollars; withdrawals of contributions and earnings are taxed as income.
- Roth 401(k) (designated Roth): contributions are made with after-tax dollars, with no income limit to participate; qualified withdrawals (account held at least 5 years and taken at or after 59½, on disability or at death) are tax-free. Roth and pre-tax deferrals share one per-person limit, $24,500 in 2026 (IRS IR-2025-111).
- Roth IRA: an account you open yourself with after-tax dollars. For 2026, eligibility to contribute phases out at MAGI of $153,000–$168,000 for single filers and $242,000–$252,000 for married couples filing jointly, and the $7,500 limit is shared with any traditional IRA (IRS IR-2025-111).
Which fits depends on your current versus expected tax rate and what your plan offers; this is general information, not tax advice.
How Much to Save in Your 20s on Different Salaries
Monthly employee contributions at 5%, 10% and 15% of pay, with an example match shown separately. Assumed formula (illustration only): 50% of your contributions up to 6% of pay, so the match tops out at 3% of salary. Your plan may differ or offer no match.
| Annual Salary | 5% of Pay (You + Example Match) | 10% of Pay (You + Example Match) | 15% of Pay (You + Example Match) |
|---|---|---|---|
| $30,000 | $125 + $63 match | $250 + $75 match | $375 + $75 match |
| $40,000 | $167 + $83 match | $333 + $100 match | $500 + $100 match |
| $50,000 | $208 + $104 match | $417 + $125 match | $625 + $125 match |
| $60,000 | $250 + $125 match | $500 + $150 match | $750 + $150 match |
| $75,000 | $313 + $156 match | $625 + $188 match | $938 + $188 match |
Starting at 30 or 35? Here’s How to Catch Up
Example (illustrative only): a steady 7% effective annual return, with deposits at the end of each month until age 65. Real returns go up and down, can be negative, and are never guaranteed.
| Start Age | Years to 65 | Monthly Deposit Needed | Total You Put In | Value at 65 (Example) |
|---|---|---|---|---|
| 25 | 40 | $200 | $96,000 | ~$494,308 |
| 30 | 35 | ~$289 | ~$121,309 | ~$494,308 |
| 35 | 30 | ~$423 | ~$152,166 | ~$494,308 |
How to check it: future value = monthly deposit × [((1 + rm)months − 1) ÷ rm], with rm = 1.071/12 − 1. Rerun any row with the SEC’s free compound interest calculator on Investor.gov. Waiting 10 years means depositing about $56,000.0 more of your own money for the same result. To plug in your own numbers, try our retirement calculator.
The levers you control are the match, a higher contribution rate (1–2 points with each raise, up to the 2026 limits above) and time in the market; taking more investment risk to “make up time” is not a reliable substitute.
Automate Your Contributions
Defaults matter. In Vanguard’s How America Saves 2026 report (2025 data), automatically enrolled employees in workplace plans had a 94% participation rate, compared with 64% in plans where employees had to sign up themselves, a gap of about 30 percentage points.
Don’t Cash Out Your Retirement Account Early
Early withdrawals are not rare: in Transamerica’s 2025 survey, one in four Gen Z workers (26%) said they had taken a hardship or early withdrawal from a 401(k), similar plan or IRA. Per the IRS, amounts withdrawn from an IRA or retirement plan before age 59½ generally owe an additional 10% early withdrawal tax, on top of regular income tax, unless an exception applies.
The bigger cost is lost growth. Example: $1,000 left invested for 40 years at an assumed 7% yearly return grows to about $14,974 ($1,000 × 1.0740). That’s illustrative, not guaranteed. Keep your emergency fund separate so a car repair never has to come out of your 401(k).
Name Your Beneficiaries
When you open a 401(k) or IRA, name a beneficiary and review it after major life changes. FINRA notes that retirement accounts pass directly to named beneficiaries and that beneficiary designations typically override instructions in a will; for employer plans, a spouse is typically required to be the primary beneficiary unless they sign a waiver.
The Asset Allocation Mistake in Your 20s
The fix: Many long-horizon investors in their 20s hold a high share of stocks, but the right asset allocation depends on your risk tolerance, timeline and emergency savings. This is educational information, not personalized investment advice.
A target-date fund typically shifts from mostly stocks toward bonds as the year in its name approaches; that schedule is its glide path. The SEC’s investor bulletin notes that funds with the same target date can hold different investments, follow different glide paths and charge different fees, and none guarantees retirement income, so compare the mix and expense ratio before you pick one.
Retirement Planning FAQ
How much should I have saved for retirement by 30?
Fidelity’s guideline suggests 1x your annual salary by age 30 (a multiple of salary, assuming you save 15% a year from age 25 and retire at 67). In practice, Vanguard’s How America Saves report shows the median account balance for participants aged 25–34 in Vanguard-administered plans was $18,732 in 2025, so focus on raising your savings rate steadily from 5% toward 15%.
Should I contribute to a 401(k) or a Roth IRA first in my 20s?
Start with your employer’s 401(k) up to the full company match first — matching formulas vary by plan (for example, 50 cents per dollar up to a set percentage of pay) and employer contributions may be subject to vesting. Next, fund a Roth IRA (up to $7,500 in 2026 across all IRAs, if your MAGI allows) to lock in tax-free growth while you’re in a lower tax bracket, then return to your 401(k).
Should I save for retirement or pay off debt first?
Capture any employer 401(k) match first, then consider prioritizing high-interest credit card debt. With the average APR on credit card accounts assessed interest at 22.36% in August 2026 (Federal Reserve G.19), paying down high-rate cards is a guaranteed saving, while investment returns are not guaranteed. Compare the snowball and avalanche strategies in our guide to paying off high-interest debt, or check your payoff timeline in the debt payoff calculator.
Is there a chart for saving for retirement in your 20s?
Yes. The compound growth table in this guide assumes $5,000 invested at the end of each year at a constant 7% annual return until 65, not adjusted for inflation and before fees and taxes: starting at 22 reaches about $1,238,882, at 25 about $998,176, at 30 about $691,184 and at 35 about $472,304. It is an illustration, not a prediction.
Is there a calculator for saving for retirement in your 20s?
Yes. The SEC’s free Investor.gov compound interest calculator lets you test your own monthly amount, return and timeline. If debt is competing with saving, our debt payoff calculator shows how long payoff will take.
What about Social Security — will it be there?
Yes. Reserve depletion does not mean Social Security stops paying benefits, though scheduled benefits may be reduced if Congress does not act. The 2026 Social Security Trustees Report projects the retirement (OASI) trust fund reserves will be depleted in late 2032, after which continuing program income would be sufficient to pay about 78% of scheduled benefits. On a combined OASDI basis, reserves are projected to last until the third quarter of 2034, when 83% of scheduled benefits would be payable (2026 Trustees Report, released June 9, 2026).
The Bottom Line
How to plan for retirement in your 20s isn’t complicated. It’s uncomfortable.
But you have time, and nobody can take that advantage from you. At a 7% effective annual return, $100 a month from age 25 grows to roughly $247,000 by 65. Someone waiting until 40 would need about $316 a month at 7% for 25 years to reach the same finish line (or about $450 a month at 10%), using the same convention.
Start with $25. Set up the automatic transfer. Forget about it for 5 years.
- Build your foundation: 15 Budgeting Tips That Actually Work in 2026
- Invest what you free up: How to Start Investing for Beginners in 2026
- Earn outside your job: How to Make Passive Income in 2026
- Clear high-interest cards: How to Pay Off Debt in 2026
- Real estate on a small budget: How to Invest in Real Estate With Little or No Money
- Free up grocery money: how to make budget-friendly meals
Disclaimer: This MoneyPulsar article is for general educational purposes in the United States and is not personalized financial, investment, or tax advice. Contribution limits (IRS Notice 2025-67), Social Security projections (2026 OASDI Trustees Report), and Federal Reserve credit data were verified as of November 3, 2026, and we review and update key figures when rates or rules change (see our Editorial Policy). This article contains no affiliate links. Investment returns are never guaranteed. Read our full Financial Disclaimer.
Syed Hamza Hasnain · Founder & Editor
Syed Hamza Hasnain is the Founder and Editor of MoneyPulsar. He researches and edits practical guides on budgeting, debt payoff, index investing, and retirement planning across our US and Pakistan tracks using primary regulatory sources. Learn more about our editorial process →