
Thinking of investing in mutual funds in Pakistan in 2026, but not sure where to begin? You are not alone. Maybe you can set aside Rs 5,000 a month from your household budget, or maybe you have a larger sum sitting idle in a current account. You want your savings to grow, yet you do not want to put hard-earned rupees into a risk you do not fully understand.
This guide explains in plain Pakistani English how mutual funds in Pakistan actually work, what can go wrong, how to verify an Asset Management Company (AMC) with regulators, how fees and FBR taxes reduce your net return, and how to begin safely. There is no sales pitch and no promise of easy profit—just clear examples in Pakistani rupees (PKR) so you can make an informed decision.
Quick Answer: What are mutual funds in Pakistan? A mutual fund pools money from many savers so a professional Asset Management Company (AMC) can invest that pool across a published mix of assets—such as Treasury bills, Sukuk, bank placements, or Pakistan Stock Exchange (PSX) shares. In Pakistan, AMCs are licensed and regulated by the Securities and Exchange Commission of Pakistan (SECP), and fund assets are held by an independent trustee. Your unit value can rise or fall, so a mutual fund is not a guaranteed bank deposit.
Table of Contents
How Do Mutual Funds in Pakistan Work? (Units & NAV Explained)
Think of mutual funds in Pakistan as a shared investment basket. Instead of researching, buying, and tracking dozens of individual bonds, Sukuk, or company shares on your own, you buy units in a regulated fund. A licensed fund manager then invests the combined pool strictly according to the fund’s published Offering Document. Some funds hold short-term cash and money market instruments, while others hold government debt, Islamic Sukuk, listed shares, or a balanced mix.
Crucially, under SECP Non-Banking Finance Companies (NBFC) and Notified Entities Regulations, every mutual fund in Pakistan is legally structured as a trust. Your money is never kept in the fund manager’s personal or corporate bank account. Instead, all securities and cash belong to the fund trust and are held in custody by an independent SECP-registered Trustee (most commonly the Central Depository Company of Pakistan, CDC).
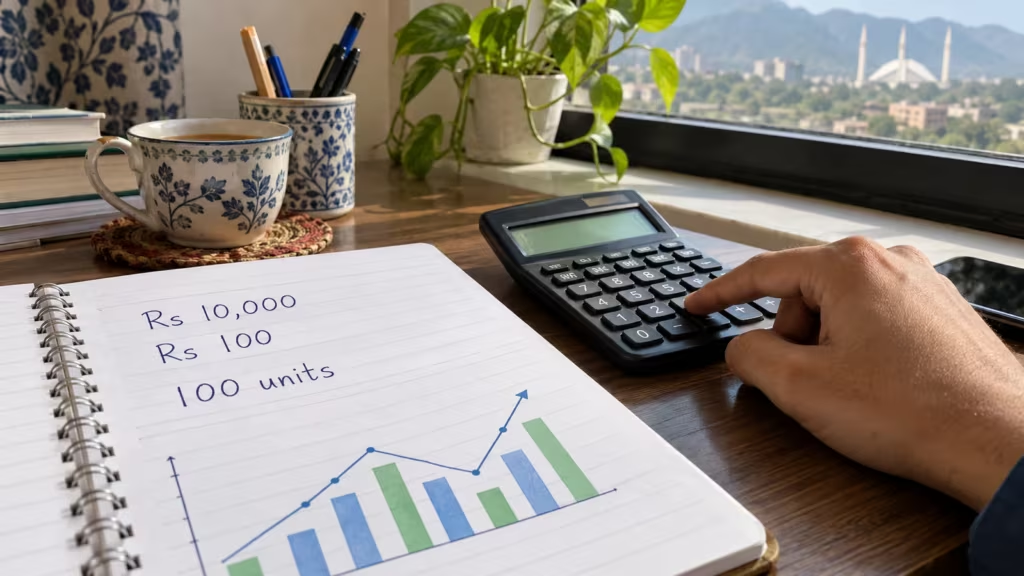
Worked PKR Example (Units & Upside/Downside Math): Imagine you invest Rs 10,000 in a fund on a day when one unit costs Rs 100. Ignoring any sales charges, you receive 100 units (Rs 10,000 ÷ Rs 100 = 100 units). If the underlying investments perform well and the unit value later rises to Rs 105, your 100 units are worth Rs 10,500 before tax and any exit charges. However, if market prices fall and the unit value drops to Rs 95, your 100 units are worth Rs 9,500. Nothing about the first scenario makes the Rs 500 gain guaranteed.
What is Net Asset Value (NAV)? The official price used to value each unit of mutual funds in Pakistan is called its Net Asset Value (NAV). A fund calculates its daily NAV by taking the total market value of all its cash and securities, subtracting permitted fund liabilities and daily accrued expenses, and dividing the remainder by the total number of units outstanding. Dealing cut-off times and pricing rules vary across funds, so the exact execution NAV may be determined at the end of the business day rather than the minute you submit your online order.
You can verify daily fund prices and category classifications across the industry on the Mutual Funds Association of Pakistan (MUFAP) Fund Directory and read investor definitions in the official MUFAP Investor FAQ.
Types of Mutual Funds in Pakistan (Risk & Category Comparison)
Not all mutual funds in Pakistan take the same kind of risk. A money market fund and an equity fund behave completely differently when interest rates or stock prices move, even when both are offered by the same bank-affiliated AMC. Always start by comparing the types of mutual funds in Pakistan by investment category and risk level, never by a catchy brand name.
| Fund Type in Pakistan | What the Fund Usually Holds | Typical SECP Risk Level & Horizon | What Beginners Need to Know |
|---|---|---|---|
| Money Market Fund | Short-term government Treasury bills, bank deposits, or short-tenor Islamic placements | Very Low to Low risk · Short-term goals (1–12 months) | Often used for accessible cash reserves, but returns change with SBP policy rates and losses remain possible. |
| Income / Fixed Income Fund | Government bonds (PIBs, T-bills), corporate debt (TFCs), or GoP/corporate Sukuk | Low to Medium risk · Medium horizon (1–3+ years) | Interest-rate movements and borrower credit risk affect unit prices; “income” does not mean a fixed guaranteed payout. |
| Equity / Stock Fund | Shares of listed companies on the Pakistan Stock Exchange (PSX) | High risk · Long-term goals (5+ years) | Can experience sharp price swings and multi-month drawdowns; unsuitable for money needed soon. |
| Balanced / Asset Allocation Fund | A combination of listed shares, fixed-income debt/Sukuk, and cash | Medium to High risk · 3–5+ years | Risk depends on the allowed equity percentage and how actively the manager shifts between stocks and debt. |
| Shariah-Compliant (Islamic) Fund | Screened PSX stocks, GoP Ijarah Sukuk, corporate Sukuk, and Islamic bank placements | Varies by sub-category (Islamic Money Market = Low; Islamic Equity = High) | Islamic status is a religious compliance filter, not a risk shield; check the specific sub-category and Shariah report. |
Both SECP’s Master Circular for Mutual Funds and MUFAP’s guide to selecting a mutual fund list additional specialized categories—including Index Tracker funds, Capital Protected schemes, Fund of Funds, and Commodity (gold) funds. The individual fund’s Offering Document and monthly Fund Manager Report (FMR) always matter more than a short marketing label.
Are Mutual Funds Safe in Pakistan? 5 Risks to Understand
When Pakistani beginners ask whether mutual funds in Pakistan are safe, the honest answer depends on separating institutional legitimacy from market risk. Investing through an SECP-licensed AMC where assets sit with a registered Trustee is fundamentally safer than sending money to an unlicensed stranger promising to double your cash on WhatsApp or Telegram. However, a 100% legitimate, regulated mutual fund can still drop in value. Regulation enforces transparency, custody rules, and audits; it never protects you from market losses, and mutual fund units are not covered by the State Bank of Pakistan’s Deposit Protection Corporation (DPC) bank guarantee.
- 1. Market risk (equity price drops): If a fund holds company shares on the PSX, economic slowdowns, political uncertainty, or company losses can push share prices—and your fund’s NAV—down sharply.
- 2. Interest-rate risk (bond and Sukuk repricing): When interest rates change, the market value of existing fixed-rate bonds, PIBs, and Sukuk inside an income fund can fluctuate.
- 3. Credit or default risk: If a corporate issuer of a Term Finance Certificate (TFC) or corporate Sukuk delays or fails to make scheduled payments, the fund holding that instrument can suffer a write-down.
- 4. Liquidity and settlement risk: In stressed market conditions, selling underlying securities quickly at fair prices can become difficult, and redemption proceeds take working days to reach your bank account.
- 5. Inflation and fee/tax erosion: Even when your nominal rupee balance grows, high inflation, annual fund management expenses, and withholding taxes reduce what your money can actually buy.
Safety rule before you send a single rupee: Always verify the company on SECP’s official Asset Management Services licensing list and confirm the fund in the MUFAP Fund Directory. Never transfer savings to a sales agent’s personal bank account or mobile wallet—only pay through the official Trustee bank account or digital billing channel named by the licensed AMC.
Mutual Funds Profit Rates in Pakistan: Why Returns Are Not Fixed
Many savers search online for mutual funds profit rates in Pakistan because they are used to bank savings accounts or National Savings certificates that publish a stated rate schedule. Most mutual funds do not have a fixed profit rate. When an AMC or MUFAP table displays a “365-day return” or “annualized return,” that percentage describes what happened over a past measurement period, not a promise about what you will earn over the next 12 months.
In particular, past returns of an equity or commodity fund can swing wildly from one year to the next, and even money market fund returns move up and down as State Bank of Pakistan (SBP) policy rates and Treasury bill yields change. A strong one-month or one-year chart should never be your sole reason to buy.
Ask these four questions whenever you inspect published mutual fund returns:
- What is the exact time period? Is the percentage a 1-month return, a year-to-date figure, a 365-day return, or an annualized money-market yield?
- Is it net of fund expenses? Published NAV returns on MUFAP are normally stated after deducting internal fund expenses (TER), but before any personal front-end sales load and personal FBR tax.
- Does it include cash dividends or only NAV movement? Some funds distribute returns primarily via cash/reinvested dividends, while others accumulate growth inside the unit NAV.
- Are you comparing apples to apples? Always compare a conventional money market fund against other conventional money market funds over the exact same date window—never against a high-risk stock fund.
If any salesperson or social media video claims “this mutual fund gives 18% guaranteed every year,” ask for the official SECP-approved Offering Document in writing and walk away from guaranteed-profit slogans. Use MUFAP’s official performance tables rather than undated screenshots.
What Fees Do Mutual Funds Charge in Pakistan?
Running a regulated fund—portfolio management, research, independent trustee custody, accounting, and SECP regulatory filings—has a real cost. When evaluating mutual funds in Pakistan, you should inspect three main cost items in the latest Fund Manager Report (FMR): the Front-End Load (FEL) or Back-End Load, the annual Management Fee, and the Total Expense Ratio (TER).
Simple PKR Fee Math (Front-End Load vs. Ongoing Expense):
- Front-end sales load illustration: Suppose you invest Rs 20,000 in a fund and a 2% front-end load is deducted from that amount. Exactly Rs 400 is taken upfront as the sales charge, leaving Rs 19,600 to buy fund units on day one. (The exact formula and tax on sales load depend on the fund’s Offering Document.)
- Ongoing annual expense illustration: Suppose a fund’s recurring annual cost (TER) is 1.0% on a flat illustrative balance of Rs 100,000. That equals Rs 1,000 over a full year. In practice, ongoing management and trustee expenses are accrued daily inside the fund and reflected automatically in the daily NAV rather than billed as a separate monthly invoice.
How to reduce front-end sales loads legally: Under SECP mutual fund regulations, the maximum permitted front-end load is capped (generally up to 3%), and regulations require a 0% front-end sales load when an investor approaches the AMC directly or invests online without a third-party distributor. Always check the fund’s current Schedule of Charges, Offering Document, and latest FMR before confirming your transfer.
Capital Gains Tax on Mutual Funds in Pakistan (2026 FBR Rules)
Understanding capital gains tax on mutual funds in Pakistan—alongside dividend withholding tax—is essential because taxes directly determine how much profit you actually keep. Tax on mutual funds can arise in two distinct ways: (1) when you sell or redeem your units for more than your purchase cost, triggering Capital Gains Tax (CGT), and (2) when a fund distributes cash or reinvested dividends to you, triggering dividend withholding tax.
Your exact deduction depends on whether your CNIC appears on the Federal Board of Revenue (FBR) Active Taxpayers List (ATL) as a Filer or Non-Filer, the type of investor (individual vs. company), the fund’s underlying income mix (equity vs. debt), and the date you acquired the units.
| Tax Event on Mutual Funds | Statutory Reference | Commonly Cited Headline Rate (Individual ATL Filer) | Non-Filer & Condition Notes |
|---|---|---|---|
| Redemption / Sale of Units (Capital Gains Tax) | FBR Income Tax Ordinance, 2001 (Section 37A / Division VII) | 15% CGT on capital gain at redemption under current framework | Higher statutory/slab rates apply to Non-Filers; rules also distinguish units by acquisition date and holding period. |
| Dividend / Distribution from Equity-Linked Income | Section 150 / First Schedule Division I | 15% WHT headline rate on equity-derived dividend component | Non-filers generally face double the filer withholding rate (30%); additional provisions can apply if a fund distributes less than 90% of income. |
| Dividend / Distribution from Debt / Money Market Income | Section 150 / First Schedule Division I | 25% WHT headline rate on debt/money-market dividend component | Non-filers generally face double the filer withholding rate (50%) on the debt-derived portion. |
These summary figures from the FBR Income Tax Ordinance (amended up to 30 June 2026) and PwC Pakistan Individual Tax Summaries are educational reference points, not a personalized tax calculation. Older unit purchase dates, specific tax credits, Zakat declarations (such as CZ-50), and Finance Act updates require checking your AMC’s current tax sheet and, where needed, consulting a qualified Pakistani tax adviser. Always download and save your annual withholding tax certificates from your AMC portal for your FBR tax return.
Are Mutual Funds Halal or Haram in Pakistan?
When readers ask whether mutual funds halal or haram applies across the board, there is no honest one-word answer for every fund in Pakistan. Conventional mutual funds and Shariah-compliant mutual funds invest in very different instruments:
- Conventional mutual funds routinely hold interest-bearing Treasury bills, Pakistan Investment Bonds (PIBs), conventional bank deposits, or shares of conventional banks and insurance companies, which do not meet Islamic finance criteria.
- Shariah-compliant (Islamic) mutual funds are governed by an independent Shariah Advisor or Shariah Supervisory Board and invest only in screened assets—such as Government of Pakistan (GoP) Ijarah Sukuk, corporate Sukuk, Islamic bank placements (Mudarabah / Musharakah), or Shariah-screened PSX stocks that pass both business-activity and financial-ratio screens.
4 checks before you treat a mutual fund as Shariah-compliant:
- Verify the exact fund category on MUFAP: Do not assume a fund is Islamic just because the parent company has a familiar Arabic or Islamic name. Check that the specific fund is listed under a Shariah Compliant category in the MUFAP Fund Directory.
- Read the Shariah Advisor’s Certificate: Every regulated Islamic fund publishes its Shariah Advisor’s name, fatwa/certificate, and annual Shariah compliance audit report on the AMC’s website.
- Inspect the latest top holdings in the FMR: Open the monthly Fund Manager Report to see exactly which Sukuk, Islamic banks, or screened shares the fund currently holds.
- Check dividend purification (charity) disclosures: For Islamic equity funds, check how any incidental non-compliant income is calculated and purified. If you need a personal religious ruling for your specific household circumstances, consult a qualified Shariah scholar rather than relying solely on a general guide.
Which Mutual Fund Investment in Pakistan Is Right for Your Goal?
Before choosing any mutual fund investment in Pakistan, start with the calendar date when you will need your cash back. Two people earning the exact same monthly salary in Pakistan often need completely different fund categories.
For example, imagine Ayesha in Lahore, who is setting aside money to pay school tuition fees in eight months, and Bilal in Karachi, who is building a long-term wealth fund he will not touch for ten years. Even if an equity fund posted a 30% gain last year, putting eight-month school-fee money into a volatile stock fund could force Ayesha to sell at a loss if the market dips right before fees are due.
| Your Goal & Timeline | What to Examine First | Important Risk Warning |
|---|---|---|
| Money needed within 12 months (e.g., school fees, emergency buffer, upcoming bill) | High liquidity, low-volatility Money Market / Cash categories, and 0% front-end/exit loads | Even lower-risk money market funds are not bank deposit guarantees. |
| Money needed in 1 to 5 years (e.g., car purchase, wedding, home renovation) | Your loss tolerance and suitable Income, Sovereign, or conservative Balanced options | Bond and Sukuk values and monthly income distributions can change when interest rates move. |
| Goal more than 5 years away (e.g., long-term wealth building, children’s university fund) | Diversified Equity, Index-Tracker, or Asset Allocation categories matching your risk capacity | Equity drawdowns can be large and multi-year recovery is never guaranteed. |
| You require Islamic investing | Fund-specific Shariah-compliant status, sub-category risk level, and Shariah audit reports | Shariah-compliant does not mean risk-free; an Islamic equity fund still carries high stock market risk. |
As MUFAP’s investor selection framework emphasizes, always match your investment objective, risk tolerance, time horizon, and total charges before picking a fund. If losing part of a sum would leave you unable to pay rent, utilities, or medical bills, keep that essential buffer in a liquid, protected bank account first. For a broader comparison of how mutual funds fit alongside National Savings, PSX Sahulat accounts, and gold, read our pillar guide to the best investment options in Pakistan for beginners.
How to Invest in Mutual Funds in Pakistan: 7 Practical Steps
If you are ready to learn how to invest in mutual funds in Pakistan, follow this seven-step checklist so you verify every regulatory and cost detail before transferring a single rupee:
- Decide your purpose and timeline: Write down the exact rupee amount you can invest today (or monthly) and the date when you expect to need the money back.
- Choose a suitable category first: Select Money Market, Income, Equity, or Shariah-compliant categories based on your time horizon and risk capacity—not a single “top return” advertisement.
- Verify the AMC and the fund: Confirm that the Asset Management Company holds an active license on SECP’s official NBFC portal and that the exact fund appears in the MUFAP Fund Directory.
- Read the Offering Document and latest Fund Manager Report (FMR): Check the investment objective, asset holdings, SECP risk profile label, Management Fee, Total Expense Ratio (TER), front-end/back-end loads, minimum investment, and redemption cut-off rules.
- Open an investment account directly with the AMC: Use the AMC’s official website, verified mobile app, or physical branch. Typical requirements include your valid CNIC, a personal bank account IBAN in your own name, mobile number verification, and standard KYC/fatca/zakat declarations (such as a Sahulat/digital account for smaller balances or a full account for larger limits).
- Transfer funds only through the approved Trustee/AMC channel: Pay from your own bank account via IBFT, Raast, 1Link biller, or crossed cheque payable to the fund’s Trustee account. Save your payment receipt and verify the unit allotment statement and applicable NAV date.
- Review periodically, not every hour: Check your monthly account statement and the AMC’s monthly FMR to ensure fees, risk, and category allocation still fit your goal. Never share OTP codes, PINs, or portal passwords with anyone.
Walkthrough: How to Check Any Fund on MUFAP & Read Its Monthly Report in 3 Minutes
Before you open an account, spend three minutes running this practical verification check on MUFAP’s public Fund Directory and the AMC’s monthly Fund Manager Report (FMR):
| What to Look Up | Where to Find It on MUFAP / FMR | What It Tells You in Plain English |
|---|---|---|
| 1. Category & Risk Profile | Top header of the MUFAP Fund Profile & FMR Page 1 | Confirms whether the fund is Money Market (Low Risk), Income (Medium Risk), or Equity (High Risk) and whether it is Shariah-compliant. |
| 2. Offer Price vs. Redemption (NAV) Price | MUFAP Daily NAV table (Offer Price vs. Repurchase Price) | If the Offer Price is higher than the Repurchase/NAV Price, the gap reflects the maximum front-end sales load. Remember to request 0% load when investing directly online. |
| 3. Total Expense Ratio (TER) & Management Fee | FMR “Fund Facts” or “Expense Ratio” box | Shows the total annual percentage deducted from the fund’s assets (including management fee, trustee fee, and SECP levy). Compare TERs across funds in the same category. |
| 4. Fund Return vs. Benchmark | FMR Performance Table (365-day / YTD / Since Inception) | Shows whether the fund manager actually kept pace with its official benchmark (such as 70% 3M PKRV + 30% bank rate for money market, or KSE-100 / KMI-30 for equity). |
What If I Invest Rs 5,000, Rs 10,000 or Rs 25,000 Every Month?
Regular monthly saving makes getting started with mutual funds in Pakistan much easier because you do not need hundreds of thousands of rupees on day one.
To understand how monthly contributions add up over three years (36 months), review the hypothetical table below. It assumes contributions at the end of each month, monthly compounding at constant illustrative annual rates (0%, 6%, and 10%), and ignores FBR taxes, sales loads, ongoing fees, and market ups and downs. It is a mathematical illustration of a savings habit, not a forecast or guarantee of fund returns.
| Monthly Saving (PKR) | Total Cash Saved in 36 Months | At 0% Hypothetical | At 6% Hypothetical Annual Rate | At 10% Hypothetical Annual Rate |
|---|---|---|---|---|
| Rs 5,000 / month | Rs 180,000 | Rs 180,000 | Rs 196,681 | Rs 208,909 |
| Rs 10,000 / month | Rs 360,000 | Rs 360,000 | Rs 393,361 | Rs 417,818 |
| Rs 25,000 / month | Rs 900,000 | Rs 900,000 | Rs 983,403 | Rs 1,044,546 |
Important reality check: Notice that over a short three-year window, most of your ending balance comes from your own disciplined monthly cash contributions (`Rs 180,000`, `Rs 360,000`, or `Rs 900,000`), not from investment gains. Also, if you are carrying high-interest credit card or personal loan debt, clearing that expensive debt first almost always saves more than a fund reliably earns; you can test how extra monthly payments shorten debt timelines using our free debt payoff calculator.
National Savings vs. Mutual Funds in Pakistan: Quick Comparison
Many Pakistani households compare Central Directorate of National Savings (CDNS) schemes with mutual funds in Pakistan. The two products have completely different legal structures: National Savings certificates and accounts follow government scheme-specific rules and revision schedules, whereas mutual funds are pooled market investments whose unit values and payouts move with their underlying assets. Never compare them by looking only at a single headline percentage.
| Comparison Question | National Savings Scheme (CDNS) | Mutual Fund in Pakistan (SECP / AMC) |
|---|---|---|
| Who sets the product rules? | Government of Pakistan / Ministry of Finance scheme-specific rules | AMC Offering Document governed by SECP NBFC regulations and Trustee oversight |
| How does the return work? | Depends on the specific certificate/account and current official CDNS rate schedule | Not fixed; daily NAV and distributions rise or fall with underlying investments |
| How do withdrawals work? | Scheme-specific lock-in rules and early-encashment service charges may apply | Open-end fund cut-off times, any applicable back-end load, and working-day bank settlement |
| What are the main risks? | Rate revisions on new deposits, inflation, tax, and early-exit deduction rules | Market, interest-rate, credit, and liquidity risks vary by fund category |
| Best way to compare them? | Match your exact time horizon, FBR filer/non-filer tax rate, Shariah preference, liquidity needs, and risk tolerance. | |
Before choosing either route, read the official terms of the exact National Savings certificate (such as Regular Income, Behbood, Defence Savings, or Sarwa Islamic accounts) and the exact mutual fund’s Offering Document rather than treating “National Savings” or “mutual funds” as a single uniform product. To compare current returns scheme by scheme, see our guide to National Savings profit rates for 2026.
How Do I Withdraw My Money From a Mutual Fund?
For standard open-end mutual funds in Pakistan, you can request a partial or full withdrawal—called a redemption—through the AMC’s online portal, mobile app, or branch. Your units are redeemed at the applicable Net Asset Value (NAV) based on the fund’s published dealing cut-off time (for example, requests submitted before the business-day cut-off receive that day’s NAV, while requests after cut-off or on weekends roll to the next business day).
Under SECP regulations, open-end mutual fund redemptions must be settled within a maximum of six working days, and many money market funds transfer proceeds to your registered IBAN in one to two working days (or offer limited instant/same-day bank transfer features subject to provider limits). However, you should never assume “instant cash” unless your specific AMC states the terms in writing. Always check the cut-off time, any back-end/contingent load, and Capital Gains Tax deduction a few days before you need the money for a fixed payment.
Common Mistakes to Avoid With Mutual Funds in Pakistan
- Chasing last month’s winner: Buying a fund solely because it topped a 30-day or 1-year return chart without checking the risk it took to get there.
- Putting short-term bill money into equity funds: Using a volatile stock fund for house rent, school fees, or emergency medical cash due within a year.
- Ignoring front-end loads and annual TER: Paying a 2%–3% sales load through an agent when direct online investment with the AMC may qualify for a 0% front-end load.
- Confusing a money market fund with a bank deposit: Forgetting that even low-risk funds are market-linked trusts and are not covered by SBP’s DPC bank deposit insurance.
- Sending money to unverified WhatsApp “agents”: Transferring rupees to a personal bank account or EasyPaisa/JazzCash number instead of the official Trustee account of an SECP-licensed AMC.
- Assuming every fund from an Islamic brand is halal: Failing to check the individual fund’s Shariah-compliant classification and Shariah Advisor report.
- Comparing pre-tax fund returns with after-tax numbers: Ignoring how FBR Active Taxpayers List (ATL) filer vs. non-filer withholding taxes change your net take-home return.
- Believing “SECP regulated” means zero loss: Assuming regulatory supervision guarantees positive returns regardless of market conditions.
FAQs: Mutual Funds in Pakistan
What are mutual funds in Pakistan?
They are pooled investments managed by a licensed Asset Management Company (AMC) regulated by SECP. Investors buy and own fund units rather than individual securities. Each fund follows a published investment strategy, and its Net Asset Value (NAV) and distributions may move up or down.
How much money do I need to start investing in mutual funds in Pakistan?
Minimum investment amounts for mutual funds in Pakistan depend on the individual fund and its Asset Management Company (AMC). Many mutual funds in Pakistan allow initial investments starting around Rs 1,000 to Rs 5,000, but you should always check the latest offering document or official account-opening page rather than assuming one minimum applies to all funds.
Are mutual funds in Pakistan guaranteed by SECP?
No. For mutual funds in Pakistan, the Securities and Exchange Commission of Pakistan (SECP) licenses and regulates Asset Management Companies and sets legal rules for fund custody and disclosures, but regulated mutual funds in Pakistan can still lose value when market prices or interest rates move.
Can I invest Rs 5,000 per month in mutual funds in Pakistan?
Yes, depending on a fund’s minimum subsequent contribution and payment arrangements, regular monthly contributions of Rs 5,000 into mutual funds in Pakistan are widely supported across money market, income, and equity categories. Confirm the exact minimum and any front-end load with the AMC before setting up a monthly transfer.
Which mutual funds in Pakistan are best for beginners?
There is no single option among mutual funds in Pakistan that is best for every investor. When comparing mutual funds in Pakistan, start with your specific financial goal, when you will need the money, how much temporary loss you can tolerate, whether you require Shariah compliance, and the fund’s Total Expense Ratio (TER) and sales loads.
Are mutual funds halal or haram?
The answer depends on the specific fund, its underlying investments, and its Shariah governance. Conventional money market and income funds hold interest-bearing instruments, while designated Shariah-compliant mutual funds invest in screened equities, Sukuk, and Islamic bank placements under an independent Shariah Advisor. Always check the fund’s official Shariah-compliant designation and annual Shariah audit report.
What is the profit rate for mutual funds in Pakistan?
Mutual funds in Pakistan do not pay a fixed, guaranteed profit rate. Instead, they publish historical performance figures (such as 30-day, 365-day, or annualized returns) based on changes in Net Asset Value (NAV) and dividend distributions, which will change in the future.
How long does withdrawal take from mutual funds in Pakistan?
For mutual funds in Pakistan, redemption timing varies by fund category, daily cut-off time, working days, and AMC procedures. Under SECP rules for mutual funds in Pakistan, open-end redemptions must be settled within a maximum of six working days, and many money market funds process requests faster on business days. Read the fund’s latest redemption rules before you need the cash.
Can I lose my original investment in mutual funds in Pakistan?
Yes. With mutual funds in Pakistan, unit prices (NAV) can fall due to stock market drops, interest-rate shifts, or credit events, and front-end sales loads, annual expenses, and FBR taxes on mutual funds in Pakistan also affect the net amount you receive.
Where can I check if mutual funds in Pakistan are genuine?
To verify mutual funds in Pakistan, start by checking the Asset Management Company on the official SECP NBFC licensing portal and looking up the fund in the MUFAP Fund Directory, then confirm bank trustee details directly on the AMC’s official website.
Final Thought: Understand the Investment Before You Make It
Mutual funds in Pakistan can be a practical, regulated way to put your savings to work without picking individual stocks or bonds on your own. However, the right fund is never the one with the loudest social media advertisement. It is the fund whose category risk, fee structure, Shariah status, and redemption timeline genuinely fit your household goals.
Start with a clear purpose, verify the AMC on SECP and MUFAP portals, read the monthly Fund Manager Report, and keep cash you need soon out of volatile assets. If you want to compare mutual funds with other regulated options in Pakistan, read our complete guide to the best investment options in Pakistan for beginners.
Official Sources, Methodology & Editorial Disclosure
How We Researched This Guide: We checked the SECP NBFC licensing framework and Master Circular for Mutual Funds, MUFAP investor education materials and live Fund Directory structure, FBR Income Tax Ordinance (amended to 30 June 2026) and PwC Pakistan tax summaries, and MoneyPulsar editorial standards. We explain fund structures, risks, and verification steps rather than rank specific commercial products. MoneyPulsar does not receive compensation from any Asset Management Company for mentioning or explaining fund categories in this article.
- Securities and Exchange Commission of Pakistan (SECP) — Asset Management Services NBFC Licensing
- Mutual Funds Association of Pakistan (MUFAP) — Investor Education & Mutual Fund FAQs
- MUFAP — Selecting a Mutual Fund (Objective, Risk, Time Horizon & Costs)
- MUFAP — Official Mutual Fund Directory & Daily NAV Profiles
- Federal Board of Revenue (FBR) — Income Tax Ordinance, 2001 (Amended up to 30 June 2026)
- PwC Worldwide Tax Summaries — Pakistan Individual Income Determination (Capital Gains & Dividends)
- SECP — Master Circular for Mutual Funds / Collective Investment Schemes / Investment Advisory Services
- Central Depository Company of Pakistan (CDC) — Trustee & Custodial Services for Collective Investment Schemes
Editorial & Financial Disclaimer: MoneyPulsar is an independent educational publication, not an SECP-licensed investment adviser, broker, or tax consultant. This article is general educational information for Pakistan, not an offer, solicitation, fund recommendation, or personalized financial, tax, or Shariah ruling. Mutual fund unit values (NAV) and distributions can go down as well as up, and you may receive back less than you invest. All PKR numerical examples and 36-month tables are hypothetical illustrations that ignore market fluctuations. Information was checked against published sources as of October 2026; always verify current AMC Offering Documents, MUFAP data, SECP circulars, and FBR tax laws before acting. Read our full Financial Disclaimer.
Syed Hamza Hasnain · Founder & Editor
Syed Hamza Hasnain is the Founder and Editor of MoneyPulsar. He researches and edits practical guides on budgeting, debt payoff, index investing, and retirement planning across our US and Pakistan tracks using primary regulatory sources. Learn more about our editorial process →