
The short answer: To create a family budget, add up your household’s take-home income, list essential expenses, set aside money for savings and upcoming bills, and track what you actually spend. Start with the 50/30/20 rule if you want a simple guide, or use zero-based budgeting if you need tighter control.
You know that feeling when payday arrives, you pay the mortgage, buy groceries, fill the car with gas, and suddenly wonder where the rest went?
You’re not alone.
Running a household is expensive. Kids need shoes without warning. Grocery bills change every week. And somehow, the car always needs repairs when the savings account is looking thin.
The good news? You don’t need a finance degree or a complicated spreadsheet to get your family spending under control.
You need a budget that reflects how your household actually lives.
This guide explains how to create a family budget step by step, with realistic US examples, a free downloadable spreadsheet, and practical ways to keep your family on the same page.
Why a Family Budget Is Different (And Harder)
A family budget is a monthly plan for how your household earns, spends, saves, and manages money. Unlike a personal budget, it must account for several people’s needs and shared responsibilities. That means planning for predictable bills while leaving room for things you can’t always predict, such as school costs or medical visits.
A single adult can decide to skip restaurants for a month. A family with two children can’t always reduce spending that easily.
Think about a family of four in Ohio earning $75,000 a year before taxes.
Their monthly gross income is $6,250. But that’s not what reaches their bank account after payroll taxes, health insurance, and other deductions.
Then come the bills.
Housing takes a large chunk. Groceries aren’t optional. Childcare might cost almost as much as another car payment.
And there’s a birthday party next Saturday.
The hidden costs that ruin family budgets
Most families remember rent, utilities, and food.
It’s the less frequent expenses that cause trouble.
School supplies show up in August. Holiday gifts arrive in December. A $900 car repair might land in March.
These costs aren’t truly unexpected. They just don’t happen every month.
That’s why you need a sinking fund.
A sinking fund is money you save regularly for a known future expense. If you expect to spend $1,200 on holiday gifts, saving $100 each month spreads the cost across the year.
The same idea works for car maintenance, annual insurance bills, and family vacations.
Here’s the thing: your budget doesn’t have to predict every surprise. It needs enough flexibility to handle ordinary family life.
The 4-Step Process to Create a Family Budget
The easiest way to make a family budget is to follow four steps: calculate your take-home income, list and prioritize expenses, choose a budgeting method, and review the results regularly. This process works whether you use paper, Excel, Google Sheets, or a budgeting app. Start simple and improve it each month.
Step 1: Calculate Your Total Household Income
Start with the money your family can actually spend.
Your take-home income is what remains after taxes and payroll deductions. It’s a better starting point than your annual salary because it reflects the money available to cover bills and savings.
Count reliable income from both partners, including wages, regular side work, and recurring support payments you actually receive.
If you take home $3,600 per month and your partner brings home $2,400, your family budget starts with $6,000.
Don’t automatically include your annual tax refund or a bonus you haven’t received.
What if your income changes every month?
Irregular income needs a different approach.
Suppose you’re self-employed and your monthly take-home pay varies from $3,200 to $5,000.
Building a budget around $5,000 could leave you short during slower months.
Instead, use a conservative income figure based on your recent records. For example, you might start at $3,200 if that’s a dependable low-month amount.
When extra income arrives, use some of it to build a cash buffer.
A buffer gives you money to cover bills during lean months without immediately relying on credit cards.
If you’re paid biweekly, remember that two months each year usually include a third paycheck. Don’t build routine expenses around those occasional extra checks.
Step 2: List and Prioritize Your Family Expenses
Family expenses should be organized into needs, wants, savings, and debt obligations. Start with housing, food, utilities, necessary transportation, and required care. Then account for minimum debt payments and planned savings. Personal spending comes after essential commitments, although the exact division depends on your family’s situation.
Look through the last three months of bank statements and credit card activity.
Don’t rely on memory. It tends to forget the little purchases.
Fixed vs. variable expenses
Fixed expenses are costs that generally stay the same from month to month, such as rent, a fixed-rate mortgage payment, or a car loan.
Variable expenses change based on use, prices, or family needs. Examples include groceries, electricity, fuel, and dining out.
Some bills, like utilities, are essential even though the amount changes.
Here’s a useful starting list. For a longer menu, see our complete list of budget categories.
| Category | Example expenses | Priority |
|---|---|---|
| Housing | Rent, mortgage, property costs | Essential |
| Utilities | Electricity, water, phone, internet | Essential |
| Food | Groceries and household basics | Essential |
| Transportation | Fuel, insurance, vehicle payments | Essential |
| Childcare | Daycare, after-school care | Essential when required |
| Healthcare | Insurance costs, prescriptions, copays | Essential |
| Lifestyle | Restaurants, subscriptions, entertainment | Flexible |
| Savings | Emergency fund, future expenses, education | Goal-based |
Don’t forget your annual bills.
If car insurance costs $1,200 every six months, your budget needs to reserve $200 per month, even if you don’t pay the bill monthly.
Money saved for a known bill is already assigned. It isn’t spare cash.
Should you save money while paying off debt?
Usually, some combination makes sense.
Keep required debt payments current. If possible, build a modest emergency cushion so a small surprise doesn’t create more borrowing.
Then review interest rates.
High-interest credit card debt may deserve faster repayment. Our guide to paying off debt compares the main payoff methods. At the same time, you may want to capture an employer’s 401(k) matching contribution if your plan offers one.
Your choices should reflect cash flow, interest costs, and financial risk.
Step 3: Choose Your Family Budgeting Method
A budgeting method is simply a rule for deciding where your income goes. The best choice is the one your household can follow consistently. Families with steady income may prefer the 50/30/20 rule, while those managing debt or tight cash flow may benefit from zero-based budgeting.
| Budgeting method | How it works | Best for |
|---|---|---|
| 50/30/20 | Divide take-home pay into 50% needs, 30% wants, and 20% savings or extra debt repayment | Beginners |
| Zero-Based | Assign every dollar to a category until income minus planned allocations equals zero | Tight budgets and debt payoff |
| Envelope | Set spending limits for categories using cash or digital balances | Controlling flexible spending |
| Flexible Budget | Cover essential bills and goals first, then manage remaining spending within a limit | Families with changing schedules |
The 50/30/20 rule
The 50/30/20 rule is a budgeting guideline that divides take-home income into three groups:
- 50% for needs
- 30% for wants
- 20% for savings and extra debt repayment
For a family taking home $6,000 per month, that means:
| Group | Percentage | Monthly amount |
|---|---|---|
| Needs | 50% | $3,000 |
| Wants | 30% | $1,800 |
| Savings and extra debt payments | 20% | $1,200 |
| Total | 100% | $6,000 |
These percentages are targets, not laws.
If your rent, childcare, and groceries already exceed $3,000, you haven’t failed. Your family has a different expense structure.
Honestly, the 50/30/20 rule is the easiest place to start. But if you’re struggling with debt or overspending, zero-based budgeting may give you better control.
What is zero-based budgeting?
Zero-based budgeting means assigning all available income to planned expenses, savings, and debt payments until nothing remains unassigned.
It doesn’t mean spending your bank account down to zero.
For example, a $6,000 income minus $4,700 in planned expenses and $1,300 in savings or extra debt payments leaves $0 unassigned.
Every dollar has a purpose.
Read our zero-based budgeting guide for a closer look.
Step 4: Track and Adjust Your Budget Every Month
A family budget only works if you compare your plan with real spending. Check transactions weekly, review category totals, and update next month’s limits based on what happened. If groceries run over budget but gas costs less than expected, adjust both categories rather than treating the whole month as a failure.
Try a 10-minute family budget check-in every Sunday.
Open your bank app. Review recent purchases. Update the spreadsheet.
If you budgeted $700 for groceries and spent $760, record the $60 difference.
Then ask what happened.
Was it higher food prices? Guests staying over? Too many midweek grocery trips?
You want an answer, not an argument. If groceries keep running over, our budget-friendly meals guide has six cheap family dinners with real costs.
At the end of the month, check three numbers: total income, total spending, and money assigned to savings.
A budget is meant to change as your family changes.
Key Takeaway
- Start with take-home income, not gross salary.
- Pay essential bills before flexible spending.
- Choose a method your household can maintain.
- Review spending weekly and revise the plan each month.
3 Real-Life Family Budget Examples
A useful family budget example shows how a household can divide a specific amount of take-home income among everyday needs, goals, and some enjoyment. The three sample budgets below are illustrative, not actual client records or national spending recommendations. Each balances to zero, meaning all income has been assigned.
Example 1: Family of Four With $6,000 Monthly Income
Imagine two working parents with two school-age children.
They bring home $6,000 each month. Both need transportation for work, and their children have some after-school care expenses.
Here’s one possible family budget:
| Monthly expense | Budget |
|---|---|
| Housing | $1,800 |
| Utilities, phone, internet | $320 |
| Groceries and household supplies | $750 |
| Transportation | $650 |
| Childcare and after-school care | $700 |
| Healthcare | $280 |
| Minimum debt payments | $250 |
| Family entertainment | $180 |
| Clothing and school needs | $150 |
| Emergency savings | $350 |
| Retirement and education savings | $350 |
| Sinking funds | $220 |
| Total | $6,000 |
This family allocates $920 to savings and sinking funds.
Their essential costs are too high to fit the classic 50/30/20 rule. That’s fairly common for households with children.
The childcare figure assumes a particular family situation, not full-time infant daycare in an expensive city.
Notice that there’s still room for family entertainment.
Removing every enjoyable activity might look good on paper, but it can make a budget difficult to maintain.
Example 2: Single Parent With $3,500 Monthly Income
A single parent often has less room for error because there’s only one main income source.
Suppose a parent has one school-age child, receives some childcare assistance, and takes home $3,500 per month, including dependable support payments.
A sample family budget might look like this:
| Monthly expense | Budget |
|---|---|
| Rent | $1,150 |
| Utilities, phone, internet | $230 |
| Groceries | $440 |
| Transportation | $310 |
| Net childcare costs | $530 |
| Healthcare | $130 |
| Minimum debt payments | $170 |
| School and clothing | $100 |
| Emergency savings | $130 |
| Sinking funds | $100 |
| Family activities | $90 |
| Small cash buffer | $120 |
| Total | $3,500 |
This budget is tight.
The $530 childcare line assumes a lower net cost after available assistance or a school-age schedule. Full-time daycare could make this plan unworkable.
The parent still reserves $350 for emergency savings, future bills, and a small buffer.
That’s meaningful progress.
If necessities exceed income, the next step may involve childcare assistance, benefit eligibility, higher earnings, or a different housing arrangement. Cutting a few subscriptions won’t solve every financial shortfall.
Example 3: Higher-Income Family With $9,000 Monthly Income
A family taking home $9,000 a month has more options, but higher income doesn’t prevent overspending.
A larger mortgage, childcare, car payments, and frequent dining out can consume that money surprisingly fast.
Here’s a sample family budget:
| Monthly expense | Budget |
|---|---|
| Housing | $2,750 |
| Utilities and communications | $450 |
| Groceries and household supplies | $1,000 |
| Transportation | $800 |
| Childcare | $900 |
| Healthcare | $400 |
| Minimum debt payments | $350 |
| Dining, travel, entertainment | $500 |
| Additional retirement/investment savings | $700 |
| 529 education savings | $400 |
| Emergency and other savings | $350 |
| Home repairs and sinking funds | $400 |
| Total | $9,000 |
This family directs $1,850 toward additional savings and future expenses.
The retirement line represents contributions made from take-home pay. Any 401(k) contributions already deducted from wages shouldn’t be counted twice.
A 529 College Savings Plan is a tax-advantaged education savings account governed by federal and state rules. Qualified withdrawals can receive federal tax benefits, according to the Internal Revenue Service.
Higher income creates opportunities, but only if you deliberately decide what to do with the extra money.
How to Create a Family Budget in Excel or Google Sheets (Free Template)
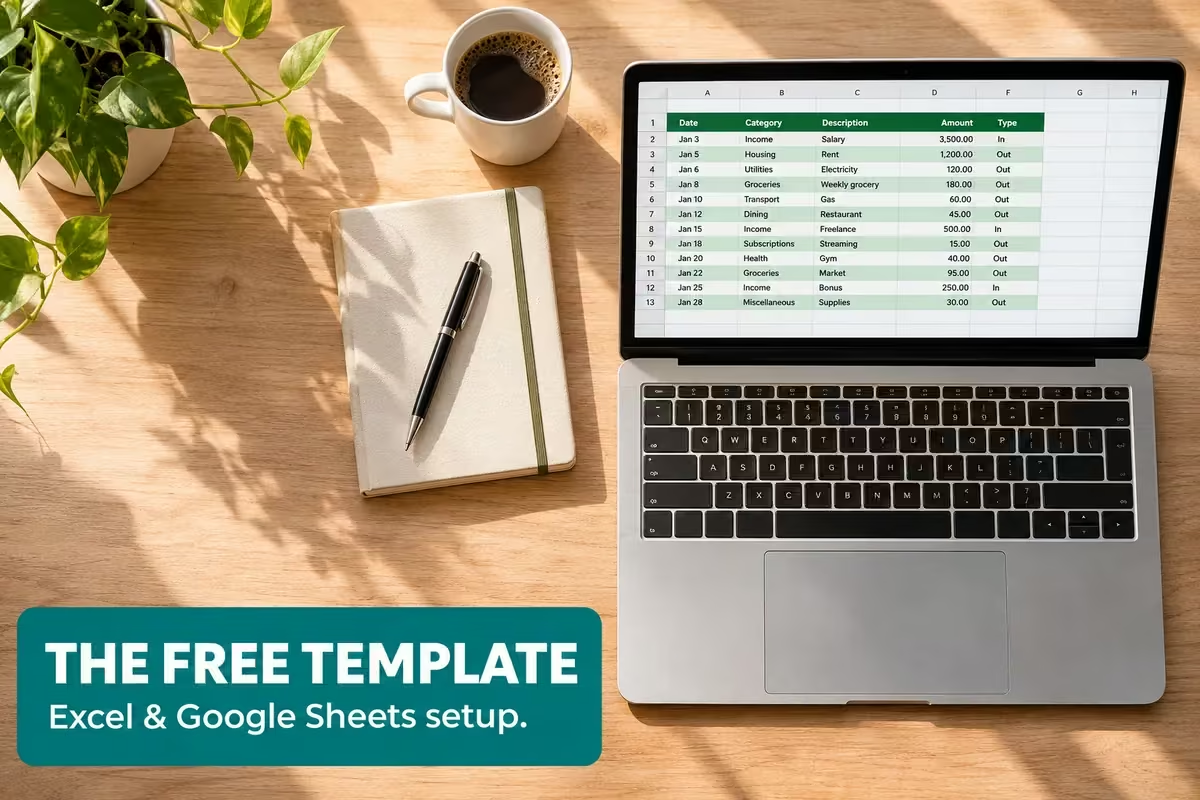
You can create a family budget template in Excel or Google Sheets without buying an app. Use one sheet to plan spending and another to record actual transactions. With a few simple formulas, the file can calculate category totals, highlight overspending, and show how much income remains unassigned.
Free download: Excel & Google Sheets
Stop Guessing Where Your Money Goes
Most families don’t overspend on purpose. They just can’t see the whole month at once. Our free Family Budget Template puts it on one screen. Log your income and expenses, and the Dashboard totals every category, splits fixed from variable costs, and shows your Net Cash Flow in one big box that turns green when you’re ahead and red when you’re not. It includes the three sample budgets from this guide, so you can see a finished plan before you build yours.
- Auto-calculating formulas: totals, categories and Net Cash Flow update as you type.
- 3 Real-Life Examples: the family-of-four, single-parent and higher-income budgets from this guide.
- Beginner-friendly: dropdown categories and a 4-step Instructions tab. No formulas to write.
Download the Free Excel Template
Your next bills are already on the way. Get your budget set up before payday. Free, one click, no sign-up.
Prefer to build your own from scratch? Here’s the do-it-yourself version.
Build your template in five minutes
Open a blank workbook and create three tabs:
Tab 1: Monthly Plan
Use these exact column headers:
| Column | Header |
|---|---|
| A | Category |
| B | Group |
| C | Planned |
| D | Actual |
| E | Difference |
Enter each expense category in column A.
Use Needs, Wants, or Savings in column B. Enter the planned amount in column C.
Column D will show what you actually spent. Column E tells you how far you are from your plan.
Tab 2: Transactions
Create these headers:
Date | Description | Category | Amount | Notes
Enter each purchase or payment here. The category names must match those in your Monthly Plan.
Tab 3: Income
Use:
Date | Income Source | Amount
Record your household’s take-home income here.
Add the formulas
In cell D2 of your Monthly Plan, use:
=SUMIF(Transactions!$C:$C,A2,Transactions!$D:$D)
This adds all transactions matching the category in A2.
In cell E2, enter:
=C2-D2
Copy both formulas down the category rows.
To calculate your total income on the Income tab, with amounts in column C, use:
=SUM(C2:C100)
Add totals for your Planned and Actual columns. Then subtract planned allocations from income to see whether your budget balances.
Keep credit card purchases in their original spending categories. Don’t count the credit card payment again as a new expense for those same purchases.
Pro Tip
Add conditional formatting to the Difference column. Make negative balances red and positive balances green. That way, you can see which categories need attention without searching through every transaction.
Keep one blank master workbook, then duplicate it each month.
How to create a family budget example PDF
Once your worksheet looks right, export the Monthly Plan as a PDF.
In Google Sheets, use File → Download → PDF. In Excel, use the PDF export or save option.
This gives you a printable family budget example PDF for monthly meetings.
Keep the spreadsheet as your editable version. The PDF works better for printing or sharing a snapshot.
You can also compare your layout with the free budgeting worksheets available from the Consumer Financial Protection Bureau.
How to Budget With a Spouse Without Fighting
The best way to budget as a couple is to agree on shared goals, make spending decisions together, and review money without blaming each other. A short weekly check-in and one longer monthly conversation can prevent small disagreements from becoming major financial arguments. Both partners should understand the household’s numbers.
Money can get personal fast.
One partner sees a $100 restaurant bill as a waste. The other sees it as a much-needed family evening.
Neither automatically has bad intentions.
The problem often begins when spending expectations were never discussed.
Try a monthly Money Date
A Money Date is a planned, low-pressure conversation about the household’s finances.
Set aside 20 to 30 minutes when the children are occupied.
Review upcoming bills, savings progress, and expenses that changed.
Avoid starting with, “Why did you spend that?”
Try, “Our grocery bill went over by $120. What should we change next month?”
That wording turns the problem into something you can solve together.
Give each partner personal spending room
A shared budget doesn’t have to mean asking permission for every small purchase.
When affordable, agree on personal spending amounts that each partner can use without debate.
The amounts don’t need to be large. What matters is having clear expectations.
If one partner earns more, that doesn’t automatically mean their preferences should control every decision.
You are managing a household, not competing for control.
And if money discussions involve threats, secrecy, or financial control, a normal budgeting meeting may not be enough. Outside support may be appropriate.
How Much Should a Family Spend Each Month?
There is no single correct monthly spending amount for every US family. The Bureau of Labor Statistics reported average spending of about $6,825 per month ($81,905 a year) in 2025 across all consumer units. But this includes different household sizes and income levels. Your family’s practical budget depends on local costs, household size, childcare, and take-home income.
What does the latest US spending data show?
The Bureau of Labor Statistics (BLS) Consumer Expenditure Surveys provide a useful national benchmark.
The original 2024 report recorded average annual spending of $78,535, or around $6,545 monthly. (BLS later revised the 2024 total slightly, to $78,527.)
The newer 2025 release (October 2026) reported average annual spending of $81,905, or approximately $6,825 monthly.
The figures cover consumer units, not specifically two-parent families with two children.
The 2024 report also showed that housing accounted for 33.4% of average spending, while transportation accounted for 17.0%.
Together, those two categories consumed roughly half of the average spending total.
That helps explain why cutting small treats alone may not transform a household budget.
Source: BLS Consumer Expenditures Report.
How much should you budget for childcare?
Childcare needs its own realistic estimate because prices vary sharply by location and child age.
The Economic Policy Institute (EPI) reported in 2025 that monthly infant-care costs ranged from $572 in Mississippi to $2,363 in Washington, DC.
For another example, EPI’s New Mexico analysis reported infant care at about $1,200 a month.
That’s a local example, not a nationwide average.
The EPI Family Budget Calculator can help you compare estimated costs for your area and family size.
If childcare costs $1,200 and your household takes home $5,000, childcare alone consumes 24% of your available income.
No budgeting method makes that number disappear.
When should you talk to a financial advisor?
Consider speaking with a qualified financial planner if you’re balancing substantial debt, retirement planning, education savings, insurance needs, or major financial decisions.
An advisor may help you compare priorities and understand tradeoffs.
Ask about credentials, fees, services, and whether the advisor acts as a fiduciary for the advice provided.
For urgent debt problems, a reputable nonprofit credit counselor may be more appropriate.
A budget won’t fix an income problem. If required expenses exceed your income, you may need additional earnings, assistance, or larger changes to your financial arrangements.
Knowing that difference matters.
Family Budget FAQs
These answers cover the most common questions about how to make a family budget, choose a budgeting method, and use a spreadsheet. The starting point is always the same: work with your real income and costs, rather than assuming another household’s numbers will fit yours.
How do I make a family budget for the first time?
Start with one month of take-home income and three months of bank and card statements. Sort your spending into bills, flexible essentials, wants, savings, and debt payments. Give every dollar a purpose, then review actual spending weekly. Your first budget is a draft, not a test you have to pass.
What is a realistic monthly budget for a family of four?
There is no universal amount. Housing, childcare, healthcare, transportation, and local prices can make two similar households spend very different sums. Start with your actual take-home pay and required bills rather than copying a national average. The $6,000 example above is a teaching model, not a recommended minimum.
How do you budget as a couple without arguing?
Hold a short weekly check-in and a longer monthly money date. Agree on shared priorities before debating small purchases, and set an equal personal-spending amount when possible. Use your budget to solve a joint problem, not audit each other. If finances feel unsafe or controlling, seek qualified support.
How do I make a family budget in Excel?
Create a Monthly Plan sheet with Category, Group, Planned, Actual, and Difference columns. Add a Transactions sheet with Date, Description, Category, and Amount. Use SUMIF to pull transactions into your plan, then compare total spending with take-home income. Review and update the file every week. Or download our free template above, which does the math for you.
Can I download a family budget example PDF?
Yes. Once you build your budget in Google Sheets or Excel, use the print or export menu to save the summary as a PDF. A PDF is handy for a family meeting or records, but keep the spreadsheet as your editable master copy. Never publish your real account details in a shared file.
Is the 50/30/20 rule good for families with children?
It can be a useful starting point, but childcare and housing may push required spending well above 50% of take-home pay. Keep essentials current first, then choose realistic amounts for savings, debt repayment, and wants. Treat the percentages as a guide, not a reason to feel you’ve failed.
How much should I save in a family budget?
Start with an amount you can repeat, even if it’s $25 per payday. Build a small emergency cushion, then work toward a reserve based on your essential expenses and income stability. Include planned annual bills in separate sinking funds so every school fee or car repair doesn’t become a surprise.
How do I budget with irregular income?
Use a conservative monthly income figure based on recent low-earning months or your dependable base pay. Pay essentials first and hold extra income in a buffer account for lean months. Track due dates as well as amounts. If your pay changes sharply, adjust your plan whenever income arrives.
What if my expenses are higher than my income?
First cover housing, food, essential utilities, transportation to work, and necessary care. Contact creditors and providers early to ask about hardship options, and check whether you’re eligible for public benefits or local aid. Cut negotiable expenses where possible, but recognize that a true income shortfall may require more income or larger structural changes.
Final Thoughts: Build a Budget Your Family Can Live With
A successful family budget doesn’t require perfection.
Some months, you’ll save more than planned. Other months, the car will need tires, school costs will jump, or an unexpected bill will arrive.
That’s normal.
What matters is knowing where your money goes and having a plan for what comes next.
Start with your actual income, cover what matters most, and give your family some room to enjoy life.
Then check your progress.
The best family budget is the one you’ll still be using six months from now.
Important Disclaimer
Not financial advice: This article is for educational purposes only and is not personalized financial, investment, tax, or legal advice. Household expenses, financial products, tax rules, and results vary. The sample budgets and the template’s example tabs use illustrative numbers, not statistics or recommendations. Consult a qualified financial professional about decisions specific to your circumstances. Read our full Financial Disclaimer.
Sources and Further Reading
- U.S. Bureau of Labor Statistics – Consumer Expenditures in 2024 (BLS Reports)
- U.S. Bureau of Labor Statistics – Consumer Expenditures, 2025 (news release)
- Economic Policy Institute – The cost of child care in every state (2025)
- Economic Policy Institute – Child care costs in New Mexico (2025)
- Economic Policy Institute – Family Budget Calculator
- IRS – 529 Plans: Questions and Answers
- Consumer Financial Protection Bureau – Your Money, Your Goals toolkit
About the Author
Syed Hamza Hasnain, Founder and Editor. He holds a BBA in Finance, has experience managing his own personal businesses, and has personal experience spot trading cryptocurrency on Binance (his own experience, not a recommendation or crypto advice). He is not a licensed financial adviser. Read more about MoneyPulsar, how we research and review content in our Editorial Policy, and our Financial Disclaimer.

Syed Hamza Hasnain · Founder & Editor
Syed Hamza Hasnain is the Founder and Editor of MoneyPulsar. He researches and edits practical guides on budgeting, debt payoff, index investing, and retirement planning across our US and Pakistan tracks using primary regulatory sources. Learn more about our editorial process →
The sinking-fund point is the strongest part of this guide — school supplies in August and a $900 car repair in March are not surprises, they are just costs that don’t happen every month, and budgeting for them monthly is what stops a good plan from falling apart. The three worked examples with real numbers help too, especially the honest note that a family of four on $6,000 can’t fit the classic 50/30/20 split. For a household where childcare already eats most of the budget, do you find the 50/30/20 rule or zero-based budgeting easier to actually stick to month after month?
Hi Muhammad, thanks for the great feedback! I’m really glad the worked examples resonated with you—especially the $6,000 family of four scenario. It’s so important to be honest that the classic 50/30/20 rule simply doesn’t work for everyone, especially right now. I also love how you phrased that: irregular costs aren’t “surprises,” they’re just costs that don’t happen every month. That is exactly why sinking funds are so powerful.
To answer your question: For a household where childcare eats up a massive chunk of the budget, zero-based budgeting is almost always easier to stick to month after month.
Here is why: The 50/30/20 rule assumes your “Needs” can comfortably fit into 50% of your income. But when you add up housing, groceries, and full-time childcare, a family’s “Needs” can easily hit 65% or 70%. When you try to force that into a 50/30/20 box, you feel like you’re failing every single month.
Zero-based budgeting gives you permission to assign every dollar a job based on your actual reality. It requires a bit more manual tracking, but it gives you total control over a tight margin.
What are you currently using to track your family’s budget?
Thanks again for reading and for the fantastic question!